
Global Markets Await Thanksgiving Pause While Oil Prices Ease on Trump's Iran Stance
Ahead of a two‑day market shutdown for Thanksgiving, global equities show modest gains while Brent and WTI crude slip after U.S. President Donald Trump's remarks on Iran.
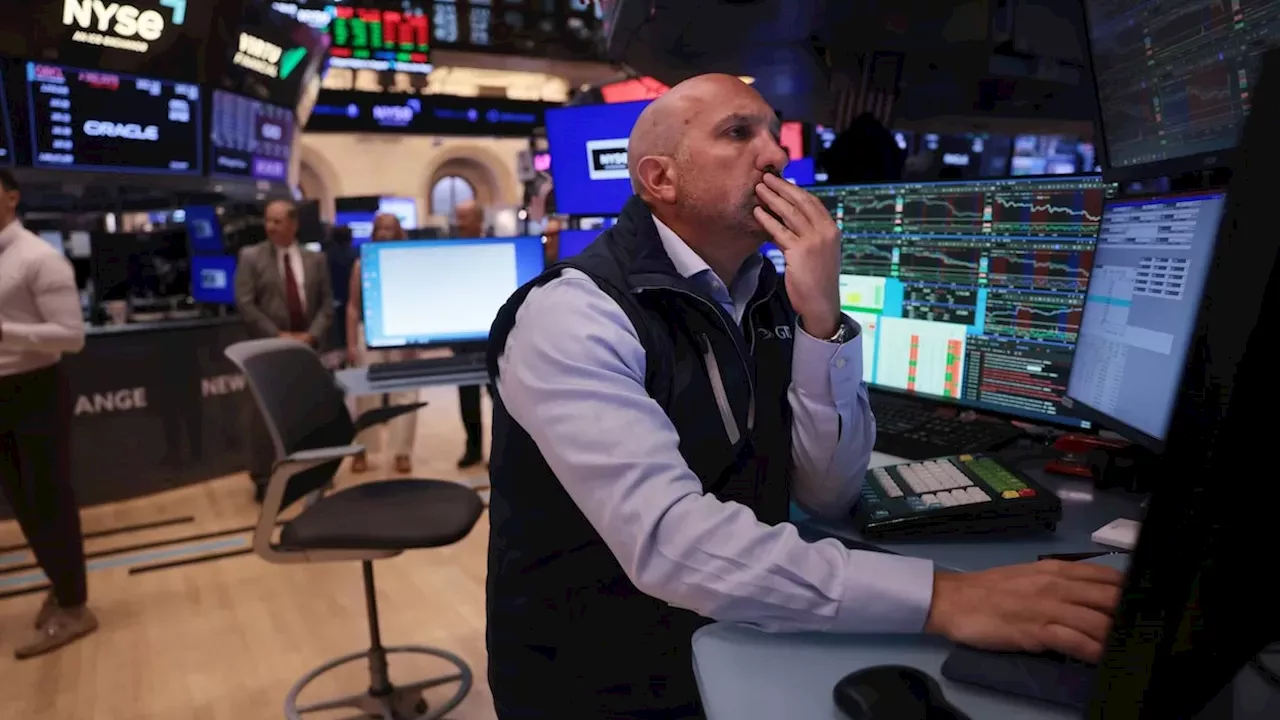
Global Markets Await Thanksgiving Pause While Oil Prices Ease on Trump's Iran Stance Ahead of a two‑day market shutdown for Thanksgiving, global equities show modest gains while Brent and WTI crude slip after U.S. President Donald Trump's remarks on Iran. Investors weigh technology fundraising prospects, high borrowing costs, and mixed earnings outlooks ahead of the U.S. midterm election cycle. Currencies remain relatively stable and bond yields suggest a cautious stance amid heightened geopolitical tensions in the Persian Gulf. The equity markets are set to close early on Thanksgiving Day, giving a two‑day break before re‑opening on Tuesday. Investors are already eyeing the upcoming pause, with most major exchanges showing a muted sentiment as they prepare to resume trading. Trump Iran Pledge Lifts Global IndicesGlobal indices were slightly uptick as oil prices slipped after President Donald Trump pledged that the United States would refrain from launching a military operation against Iran before the midterm elections scheduled for next month. The announcement eased near‑term worries about supply disruptions in the critical energy market and contributed to a modest lift in global stocks.At the same time, the market remains atmosphere of caution with a backdrop of another wave of technology fundraising, buoyed by strong capital‑raising activity. The cost of borrowing in several of the world's largest economies is still at historically high levels, adding a layer of uncertainty that weighs on risk‑seeking sentiment.As a result, investors are watching futures for the TSX and other major indices, with the Toronto Stock Exchange futures in positive territory ahead of the Canadian September employment data. In Canada, the spotlight is on company MTY Food Group Inc. while on Wall Street, financiers anticipate a close on earnings from Delta Air Lines Inc. From a macro perspective, Florian Ielpo, head of macro at Lombard Odier, notes that investors are increasingly selective with AI valuations and that the demand for safe‑haven assets like government bonds remains robust at elevated yields.European and Asian Markets Post GainsAcross the Eurozone, the pan‑European STOXX 600 closed up 0.85 per cent in morning trading, with the FTSE 100 climbing 0.8 per cent, Germany's DAX emerging 0.96 per cent higher and France's CAC 40 up 0.83 per cent. In Asia, the Nikkei index in Japan was flat, while Hong Kong's Hang Seng Index rose 1.79 per cent.Oil prices reflected a lack of dramatic move amid the President's comments, also supported by China's resumption of product exports, which contributed to a reduction in global oil prices. Wedged within the news, Brent crude futures fell 1.61 per cent to US$102.60 a barrel, while West Texas Intermediate fell 1.32 per cent to US$90.28.Oil Prices Fall While Gold SurgesAnalyst Tamas Varga from PVM Oil Associates said that although the escalation in the Persian Gulf and the Red Sea persisted, the region's oil export capacity was not expected to be long‑term supportive, and a comprehensive decline in oil prices in the near future seemed unlikely. Gold remained a bright spot for commodities as spot gold increased 1.4 per cent to US$4,190.57 an ounce.U.S. gold futures for December delivery rose 1.4 per cent to US$4,215.30, reflecting a search for safety as geopolitical concerns continued. Currency markets were largely quiet. The Canadian dollar showed minor movement against the U.S. dollar, trading around $1.4224 per US$1 over a range of 70.09 to 70.39 US cents early in the day. Over the last month, the loonie fell nearly 2.5 per cent versus the greenback.The U.S. dollar index, which weighs the greenback against a basket of currencies, declined 0.11 per cent to 102.03, while the euro rose marginally by 0.09 per cent at US$1.1223. The pound sterling saw a modest gain of 0.07 per cent to US$1.3239. Bond yields reflected a cautious stance by investors. The U.S. 10‑year Treasury yield rose last to 5.243 per cent, signalling that while the yield curve is still steep, forthcoming economic indicators could sway the market.Key Canadian And US Economic Data DueIn Canada, the September employment report is due to be released at 8:30 a.m. ET, with Wall Street expecting a net gain of 9,200 jobs compared with a loss of 41,700 jobs in August, and an unemployment rate projected to increase to 6.5 per cent. Parallelly, U.S. economists will look forward to the University of Michigan Consumer Sentiment Index release for October, expected at 10 a.m. ET pre‑market.The preliminary reading will offer insight into the average consumer's confidence view for the next few months, potentially guiding policy expectations. Together, these data points paint a picture of a market in a delicate balance, seeing optimism in certain sectors but wariness in others as it prepares to bounce back from an extended holiday break.
Original source:
Head Topics
Comments 0