
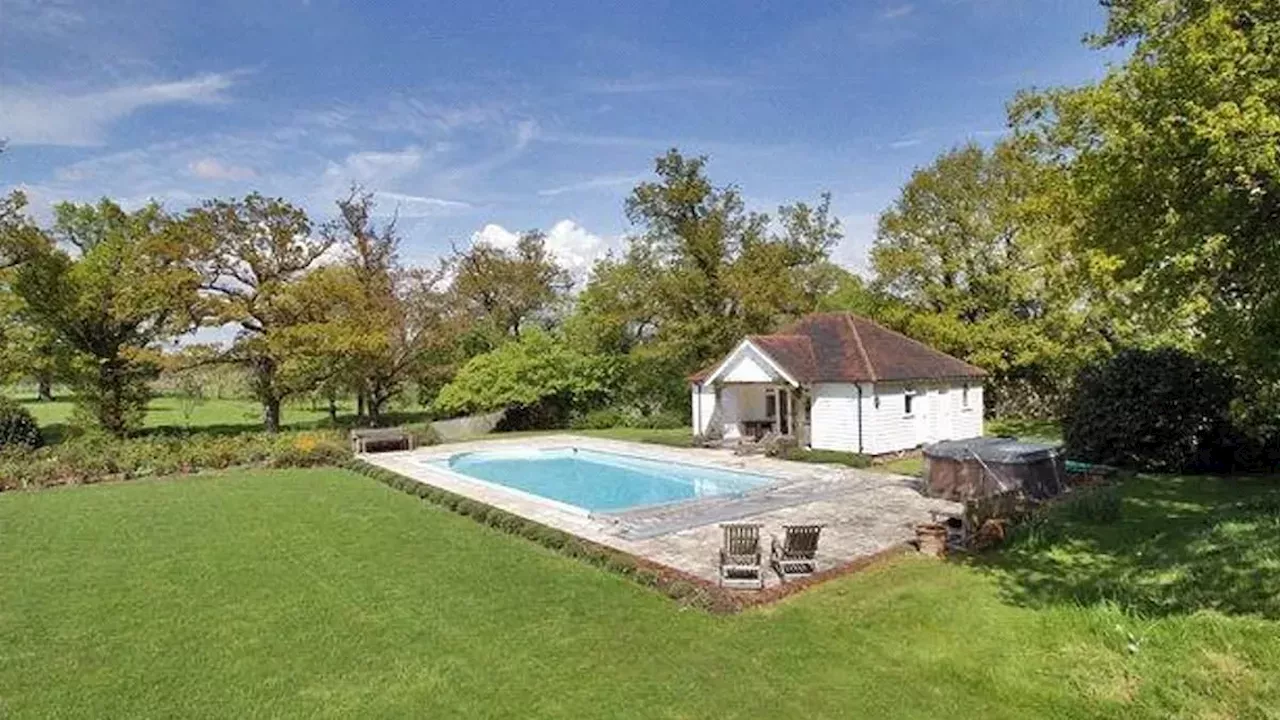
A tax tribunal has rejected a claim by John Smith to receive reduced stamp duty on his £2.6 million Kent estate. The ruling determined that a five-bedroom pool house at the Huntbourne property does not qualify as an independent dwelling.
The missing independence of the Huntbourne pool house
The structure's failure to qualify as a dwelling centered on its lack of autonomy from the main estate.. As reported by the source , the pool house lacked separate doorways, independent electricity, and secure storage, which prevented occupants from being truly self-sufficient.
Judge Rosa Pettifer noted that the physical connection to the main house was too significant to allow for true separation. Specifically, the judge pointed out that using the pool house's facilities would either require the main house residents to be excluded from the pool or force them to walk approximately 200 feet to access a toilet.
An £80,750 gap in stamp duty savings
The financial implications of the tribunal's decision are substantial for the owner of the Kent estate. Had HM Revenue & Customs accepted the classification of the pool house as a second dwelling, Smith's stamp duty obligation would have been significantly reduced.
The report states that the original stamp duty of £301,250 would have dropped to £220,500. This represents a lost opportunity for the buyer to save £80,750 through the application of reduced rates for linked properties.
Jeremy Hunt’s June 2024 crackdown on linked properties
This legal dispute follows a significant shift in UK tax policy initiated by Chancellor Jeremy Hunt. In June 2024, the government scrapped stamp duty relief that previously allowed buyers of two or more linked properties to benefit from lower rates .
The policy change was driven by concerns that the relief acted as a loophole for high-net-worth individuals. for instance, the source highlights how entrepreneur Suneil Setiya used the previous rules to reduce a stamp duty payment on a £275 million Chelsea mansion from roughly £32 million to £13 million by pairing the estate with five flats.
Will the 200-foot distance rule create new tax precedents?
The ruling leaves several questions regarding how HMRC will evaluate future estate amenities. it remains unclear how much physical distance or what specific utility independence will be required to satisfy the "basic living needs" test in future tribunal hearings.
Furthermore, the decision does not clarify how mixed-use developments or transactions involving six or more properties will be treated differently under the current regime. As the government continues to tighten tax advantages, the boundary between a luxury amenity and a legal dwelling remains a volatile area for property investors.
Comments 0