
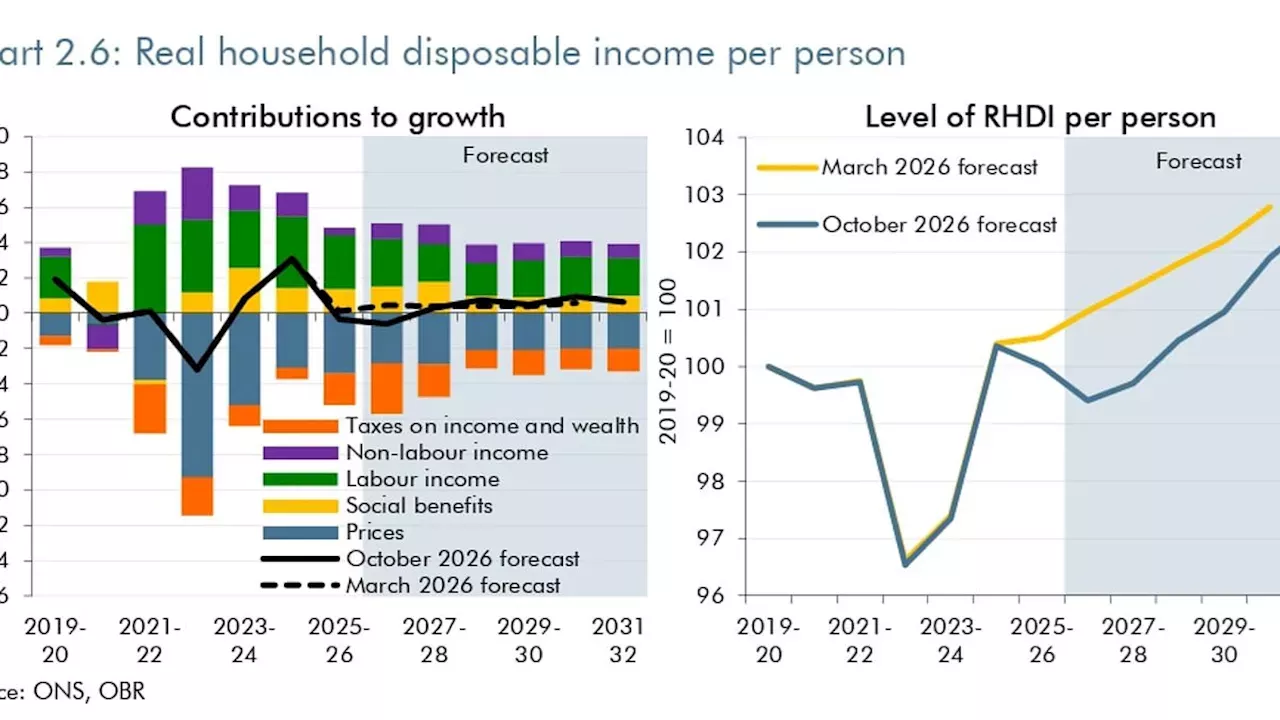
The OBR's latest forecast predicts a significant slowdown in UK household prosperity. The watchdog anticipates that real earnings will see no growth during 2027 and 2028 as economic pressures mount.
A decade of growth averaging just 0 .25%
The UK is currently navigating a period of historically weak economic performance that traces its roots back to the 2008 credit crunch. According to the OBR, growth in the ten-year period leading up to 2025-26 averaged a mere 0.25% per year. this stagnation is a direct consequence of lower productivity and suppressed real wages that have persisted for over fifteen years.
The report says that this trend is expected to deepen in the near term, with growth potentially falling even further. by the 2029-30 period, the central forecast suggests that the average annual growth over the preceding decade could drop to less than 0.1%.
The National Insurance pass-through and frozen tax thresholds
Businesses are expected to mitigtae the impact of Labour's National Insurance hikes by passing these costs directly to their employees. this mechanism, the OBR warns, will likely result in "no growth" for real earnings throughout 2027 and 2028.
Keir Starmer’s government has made improving real household disposable income (RHDI) a priority,yet fiscal structures may work against this goal.. The watchdog noted that frozen income tax thresholds create a "bracket creep" effect, where nominal wage increases lead to higher effective tax rates, thereby eroding the actual purchasing power of workers.
How the Iran war spike impacts real wage growth
Geopolitical instability in the Middle East, specifically the inflation spike triggered by the Iran war, is complicating the UK's economic recovery. The OBR reports that this conflict is exerting downward pressure on real wage growth while simultaneously driving up nominal wage figures.
This divergence creates a deceptive sense of prosperity; while workers may see higher numbers on their payslips, the actual value of that money is diminished by rising costs. This inflationary pressure acts as a secondary tax on the household, further squeezing the disposable income that the Treasury aims to protect.
Can the 0.75% recovery target be met?
The OBR anticipates a partial recovery in real household disposable income per person, projecting an average annual rise of 0.75% up to 2030-31. However, this recovery relies heavily on the expected easing of energy prices, a variable that remains subject to global volatility.
Several critical questions remain unanswered by the current budget projections.. It is unclear how much the Middle East crisis will continue to fluctuate and whether its inflationary impact will exceed current estimates . Additionally, the report does not specify how the government plans to address the productivity gap that has kept growth at historic lows since the 2008 financial crisis.
Comments 0