
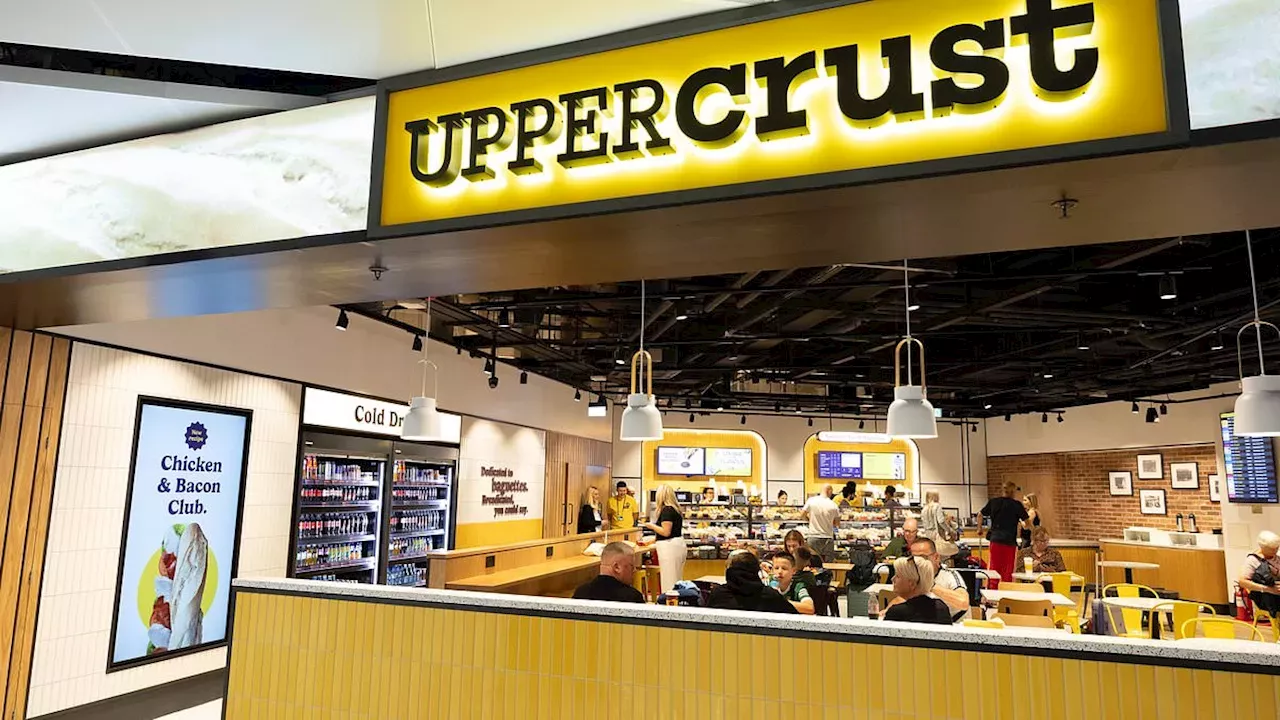
SSP, the private-equity-owned operator of food outlets like Upper Crust and Millie's Cookies, has adjusted its annual earnings expectations downward. The company anticipates operating profits of £230 million, a figure that falls short of its previous guidance due to declining passenger numbers at key international travel hubs.
The £230 million profit forecast amid regional unrest
Geopolitical instability in the Middle East is the primary driver behind the revised financial outlook for SSP. As reported by the source, ongoing tensions, including the Iran war, have led to a sharp decline in passenger traffic at the company's travel-hub sites. This downturn directly impacts the group's ability to meet its original profit targets, despite a resilient performance in other retail environments.
The company's portfolio is vast, encompassing licensed venues for major global brands such as Starbucks, Burger King, M&S Simply Food, and The Breakfast Club. While CEO Patrick Coveney has emphasized that the company's diversified regional profile should provide a cushion, the slump in the Gulf and other Middle Eastern markets remains a significant headwind for the group's annual results.
A 4 per cent sales rise cannot mask falling passenger numbers
Despite the decline in passenger volume, SSP has managed to maintain some level of sales momentum. Like-for-like sales across the group's concessions rose by 4 per cent in the three months ending in September, contributing to a total full-year revenue of £3.8 billion. This represents a 5 per cent increase year-on-year, suggesting that the company is extracting more value from the travelers who are still moving through hubs.
The growth is unevenly distributed across the company's global footprint. According to the report, the UK and Ireland saw a robust 9 per cent increase in sales, though management attributed this to stronger summer trading and outlet improvements rather than a structural shift in demand . In contrast, the US market saw a more modest 2 per cent rise in like-for-like sales during the same period, highlighting the difficulty of maintaining high-growth trajectories in a volatile global market.
Irenic Capital Management’s push for a 50 per cent valuation premium
The company's stock has faced significant downward pressure, with shares dropping 3 per cent this week alone. This recent decline is part of a larger trend; the company's market value has seen an 11 per cent loss year-to-date and remains 70 per cent below its pre-pandemic peak. This prolonged period of underperformance has made SSP a target for activist investors.
Specifically, Irenic Capital Management has emerged as a vocal critic, calling for a formal re-valuation of the food-to-go business. The investment group has urged the company's private-equity owners to consider a sale at a 50 per cent premium to its current market price. This pressure comes at a time when SSP is attempting to modernize its outlets and expand its core brands, such as Upper Crust, to maximize footfall and conversion rates .
Will the Gulf's 90 per cent recovery signal a broader turnaround?
A central question for the company's future is whether the recovery in the Middle East can gain enough momentum to stabilize earnings. while the Gulf markets have managed to bounce back to approximately 90 per cent of their pre-war levels, traffic remains notably depressed in the eastern Mediterranean, the Asia-Pacific (APAC) region, and key Indian markets. The speed at which these specific regions return to full capacity will likely dictate SSP's ability to hit its earnings per share targets.
Furthermore,the market is waiting to see if SSP's strategy of diversifying into train stations and urban retail centers will be sufficient to mitigate the risks of airport-centric revenue. While the company is investing heavily in training and technology to improve customer experiences, the heavy reliance on airport concessions means that any continued geopolitical disruption in the Middle East could continue to weigh on the bottom line.
Comments 0