
U.S. equity markets remained near all-time highs on Friday, though a significant retreat in artificial intelligence stocks pressured the Nasdaq. While oil prices saw a recovery and Treasury yields softened folowing a government bond sale, investors displayed growing caution regarding tech valuations.
Nvidia's $3.73 billion revenue beat failed to stop the slide
Despite reporting a quarterly profit that exceeded expectations and a massive $3.73 billion revenue beat, Nvidia saw its shares drop 2 .9%. This downturn was mirrored across the semiconductor sector, with Broadcom easing 4.3% and Micron Technology slumping 4.8%. According to the report, these losses pulled the Nasdaq composite down 1.3%, even as the Dow Jones Industrial Average managed a slight gain of 0.1% to reach 34,921.
The sell-off suggests a fundamental shift in investor psychology. Steven Innes of SPI Asset Management noted that the previous trend of buying any asset with an "AI label" is evolving into a more rigorous competition based on actual balance-sheet strength rather than mere ambition. This transition indicates that the market is no longer satisfied with growth promises alone,demanding concrete financial sustainability from AI-driven firms.
The $106 oil spike and Trump's Iran signals
Energy markets experienced significant volatility on Friday, with Brent crude climbing 4.1% from a previous low of $99 to reach $104.28. The report says that prices briefly touched the $106 mark after President Donald Trump suggested that talks with Iran were proving productive. However, this peak was short-lived, and U.S. benchmark crude actually dipped 0.8% to end at $90.75.
This price action highlights how sensitive global energy markets remain to geopolitical rhetoric coming from the U.S. executive branch. The rapid fluctuation between $99 and $106 underscores a fragile equilibrium where political hints regarding Iranian oil can trigger immediate, albeit temporary, price surges.
A $2 trillion deficit weighing on Treasury yields
The U.S. bond market saw a slight reprieve as the 10-year Treasury yield retreated to 5.23% from an initial peak of 5.35%.. this easing followed a Treasury auction that successfully sold $22 billion in 30-year bonds at a yield below 5.62%,which in turn pushed the 30-year yield down from 5.73% to 5.60%.
However, this relief is tempered by a daunting macroeconomic backdrop. As reported, the U.S. federal deficit reached nearly $2 trillion for the fiscal year ending September 30. This mounting debt continues to place upward pressure on yields, creating a tension between short-term auction success and long-term fiscal instability that keeps bond traders on edge.
Why Samsung and SK Hynix defied the AI slump
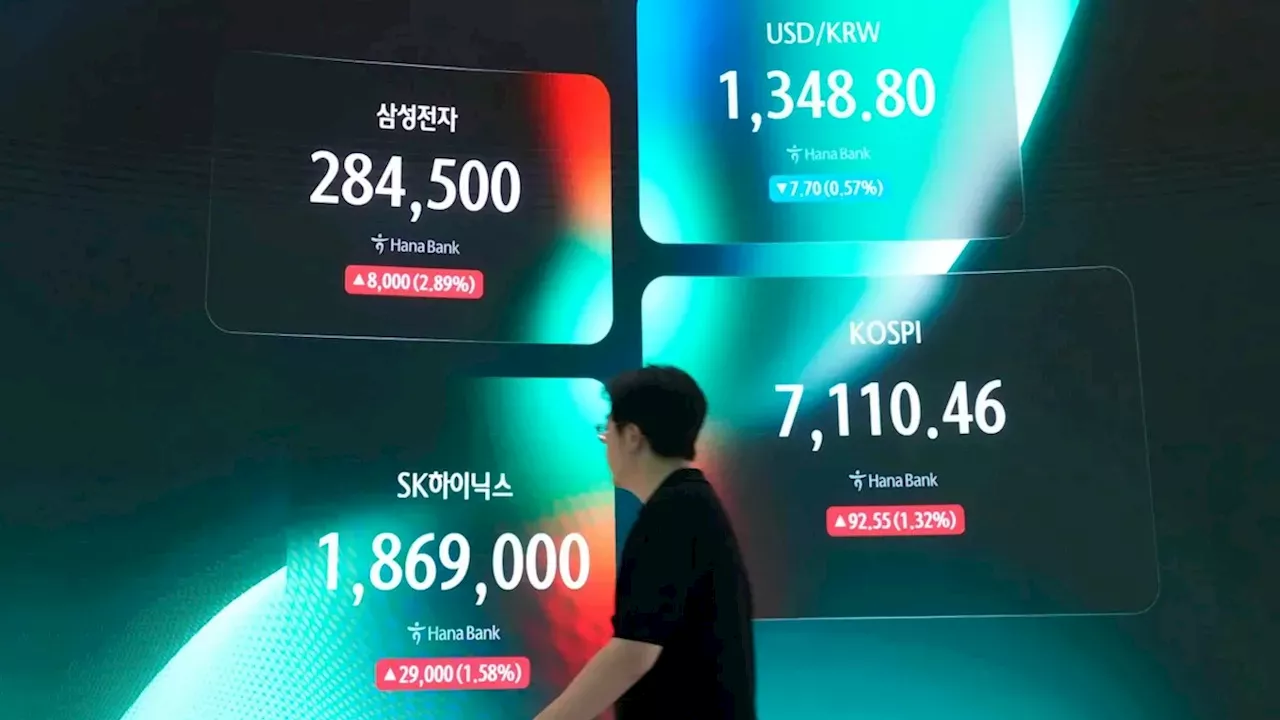
While U.S. tech stocks struggled, the Korean Composite Stock Price Index (KOSPI) remained relatively stable. Major South Korean semiconductor players, specifically Samsung Electronics and SK Hynix, managed to hold their ground despite the broader global retreat in PC and chip-related equities.
This divergence suggests that different regions are pricing AI risk differently. While Wall Street is aggressively re-evaluating the sustained demand for AI hardware, Asian markets—supported by modest gains in India's Sensex (+1 .2%) and Australia's S&P/ASX 200 (+0.6%)—appear more resilient to the immediate valuation correction seen in the Nasdaq.
The missing details on U.S. fiscal plans and Iran talks
Despite the market movements, several critical pieces of information remain missing. the source mentions that investors are awaiting "U.S. fiscal plans," but does not specify which policy changes or budget adjustments are expected. furthermore, while President Donald Trump hinted at "productive" talks with Iran, the specific terms or goals of these discussions remain unverified, leaving energy traders to speculate on the actual likelihood of increased oil flow.
Comments 0