Florida Emergency Declared Amid Historic Flooding and Insurance Concerns
Gov. Ron DeSantis declares emergency in seven Florida counties after record rainfall causes deadly floods, highlighting severe gaps in state flood insurance coverage.
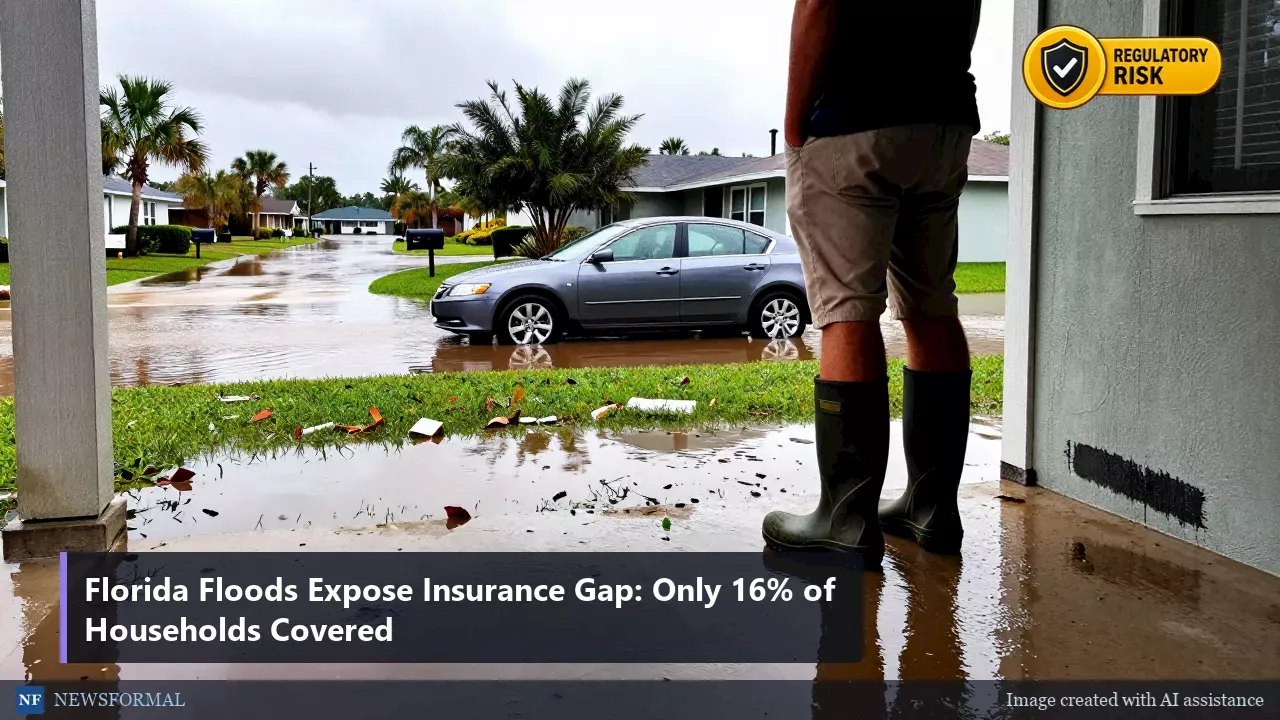
Florida Emergency Declared Amid Historic Flooding and Insurance Concerns Gov. Ron DeSantis declares emergency in seven Florida counties after record rainfall causes deadly floods, highlighting severe gaps in state flood insurance coverage. Florida Governor Ron DeSantis declared a state of emergency for seven counties following three days of extreme rainfall that caused widespread flooding and at least two deaths. The National Weather Service described the event as a '1-in-1,000-year' occurrence, with Malabar recording nearly 24 inches of rain in a single day. This historic weather pattern has exposed a critical vulnerability in the state's financial safety net, as data from AM Best reveals that only 16% of Florida households currently carry flood insurance. Extreme Rainfall Causes Deadly FloodingA slow-moving low-pressure system over the eastern Gulf of Mexico, driven by a high-pressure system off the East Coast, dumped unprecedented amounts of water across Florida's eastern seaboard. The deluge resulted in nearly 24 inches of rain in 24 hours at Malabar, almost 20 inches at Palm Bay, and 13 inches in and around Melbourne. Residents in some Palm Bay areas reported up to five feet of water inside their homes, while vehicles were seen floating down streets. Emergency responders conducted roughly 160 rescues in Brevard County, with deputies and state Fish and Wildlife officers working to save those trapped by the rising waters. Two fatalities were confirmed, including a man found in his truck.DeSantis Declares Emergency in Seven CountiesGov. Ron DeSantis declared a state of emergency for Brevard, DeSoto, Hardee, Highlands, Indian River, Martin, and St. Lucie counties. This declaration opens the door for state and federal assistance to help municipalities and residents recover from the disaster. The emergency status allows for the deployment of resources to manage the immediate crisis and supports the distribution of disaster relief funds. While this aid provides crucial support for those affected, it is important to note that disaster relief is not a substitute for insurance. The declaration does not restore uninsured homeowners to their pre-flood financial position, leaving many to bear the cost of repairs out of pocket.AM Best Warns of Unmanageable Insurance GapsAM Best, a leading credit rating agency, assessed that the financial fallout for federal and private flood insurers will be manageable due to the limited geographic footprint of the event. However, the firm used the situation to highlight a structural weakness in Florida's insurance market. The National Flood Insurance Program (NFIP) caps residential coverage at $250,000 per residence. This limit falls significantly short of Florida's approximately $400,000 median home value. Christopher Graham, senior industry research analyst at AM Best, stated that the combination of low insurance take-up rates and insufficient coverage limits leaves a significant number of homes financially exposed to uninsured losses.Underinsurance Risks Hit Florida Homeowners HardFlorida has the highest take-up rate for private flood insurance in the country, yet it trails several other states in NFIP policies. This discrepancy reflects the state's unique insurance landscape, where a large private flood market coexists with the state-run Citizens Property Insurance Corp. Private flood policies tend to concentrate in high-value coastal properties where lenders require coverage. Consequently, inland and lower-income households, including many in the counties hit by this recent event, often lack protection. A homeowner with a $400,000 median-value house who carries only NFIP coverage faces a six-figure shortfall in the event of a total loss, creating a severe financial burden for the majority of residents.Future Implications for Florida Insurance MarketsWhile the short-term flood event is unlikely to destabilize Florida's insurance market, the long-term implications are significant. AM Best noted that improvements in underwriting and pricing are making flood losses manageable for insurers, but this also implies that premiums will continue to rise for high-risk properties. This price increase could potentially widen the coverage gap further, pushing more homeowners out of the insurance market. The NFIP has faced repeated calls for reform due to its debt to the U.S. Treasury and outdated risk pricing models. As the state moves forward, the focus remains on balancing manageable insurer losses with the urgent need to protect the hundreds of thousands of homeowners who remain underinsured.
Original source:
Head Topics
Comments 0