
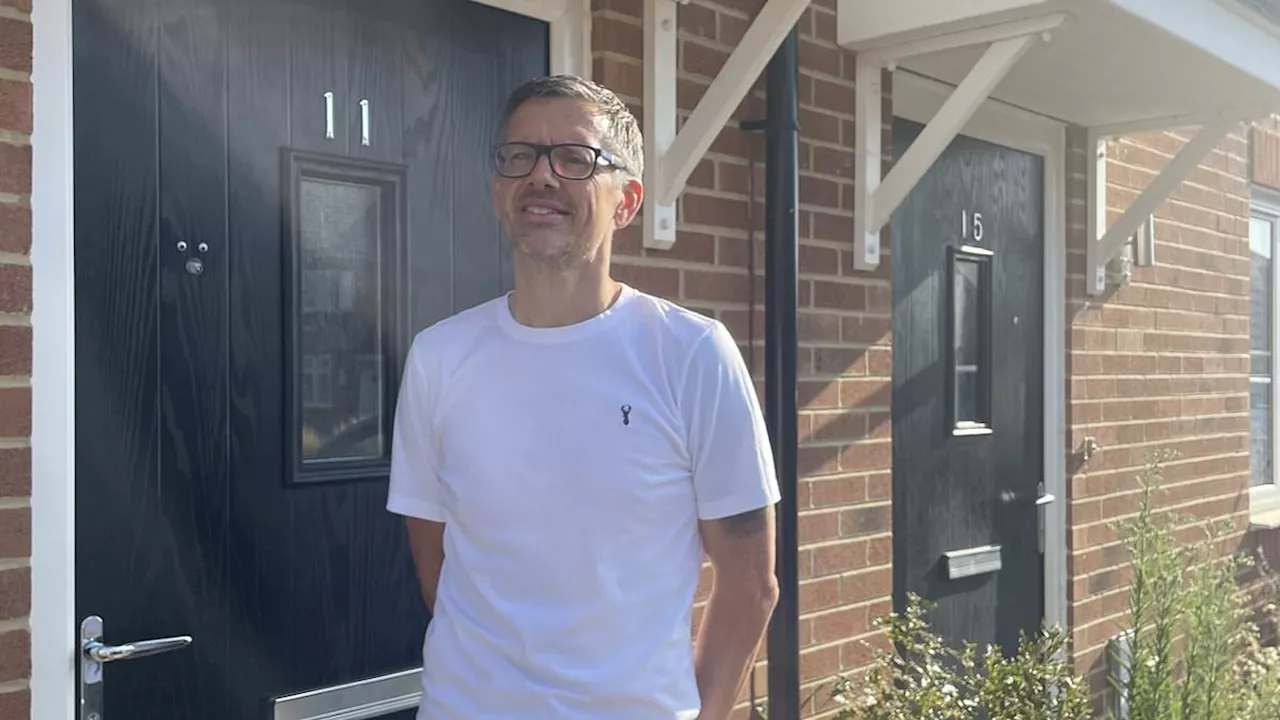
A family in Reading is facing significant financial losses because HM Land Registry (HMLR) delays have left their new build home unmortgageable. Anthony Hockham and his family are currently trapped on a high variable rate after a 26-month registration backlog blocked their remortgage application.
The £169 monthly penalty for the Hockhams' Reading home
For Anthony Hockham and his family, the dream of a £485,000 four-bedroom new build in Reading has turned into a financial burden. According to the report, the family's initial two-year fixed-rate mortgage expired earlier this year, but they found themselves unable to switch to a more competitive product. Because the title registration for their property remained incomplete, the home was deemed unmortgageable by lenders.
The financial impact is immediate and stark. The Hockhams are currently paying a 5.5 per cent standard variable rate, which totals £1,202 per month. As the report says, they had lined up a 3.49 per cent fixed-rate mortgage with Santander that would have cost only £1,032 monthly. This administrative failure is effectively costing the family £169 every month, while their original mortgage offer has expired and markket rates have climbed.
How HMLR's £19 million industry drag creates 'unmortgageable' properties
The predicament of the Hockham family is a symptom of a wider systemic inefficiency within the HM Land Registry. Banks and lenders require a clear , undisputed, and fully registered title before they will release funds for a mortgage. when the HM Land Registry fails to finalize these titles, homeowners are left in a legal limbo where they own the property in practice but cannot leverage it financially.
This is not an isolated incident of bureaucratic friction. HM Land Registry estimates that these types of registration delays may be costing the wider property industry up to £19 million every year. This systemic lag creates a precarious environment for new-build buyers who assume that the transition from developer to homeowner is a formality , only to discover that the underlying legal paperwork is missing or flawed.
Developer errors and boundary line mistakes in the registration pipeline
The root of the 26-month delay in the Hockhams' case appears to be a combination of professional negligence and administrative oversight. HM Land Registry attributed the delay to the original property developer's application, which contained errors or omissions that required months of clarification. The report notes that the developer's own registration was only completed two months before Anthony Hockham submitted his application.
Further complicating the matter were errors made by solicitors. Specifically, the boundary lines for the Hockhams' property were drawn incorrectly. These mistakes were not flagged or corrected promptly, adding another layer of delay to a process that should have been seamless. This highlights a dangerous gap in the quality control of the conveyancing process for new-build estates.
Who is accountable for the 26-month registration gap?
While the financial loss to the Hockhams is clear, the path to restitution remains opaque. The source does not specify whether there is a mechanism for homeowners to claim compensation from the HM Land Registry or the developers whose errors caused the delay. It remains unclear if the solicitors who misdrew the boundary lines will be held liable for the resulting increase in mortgage payments.
Furthermore, the report focuses on a single family's struggle, leaving open the question of how many other Reading residents or new-build owners across the UK are currently trapped on standard variable rates due to similar HMLR backlogs. Without a public database of registration delays, the true scale of this financial drain remains hidden from the public eye.
Comments 0