
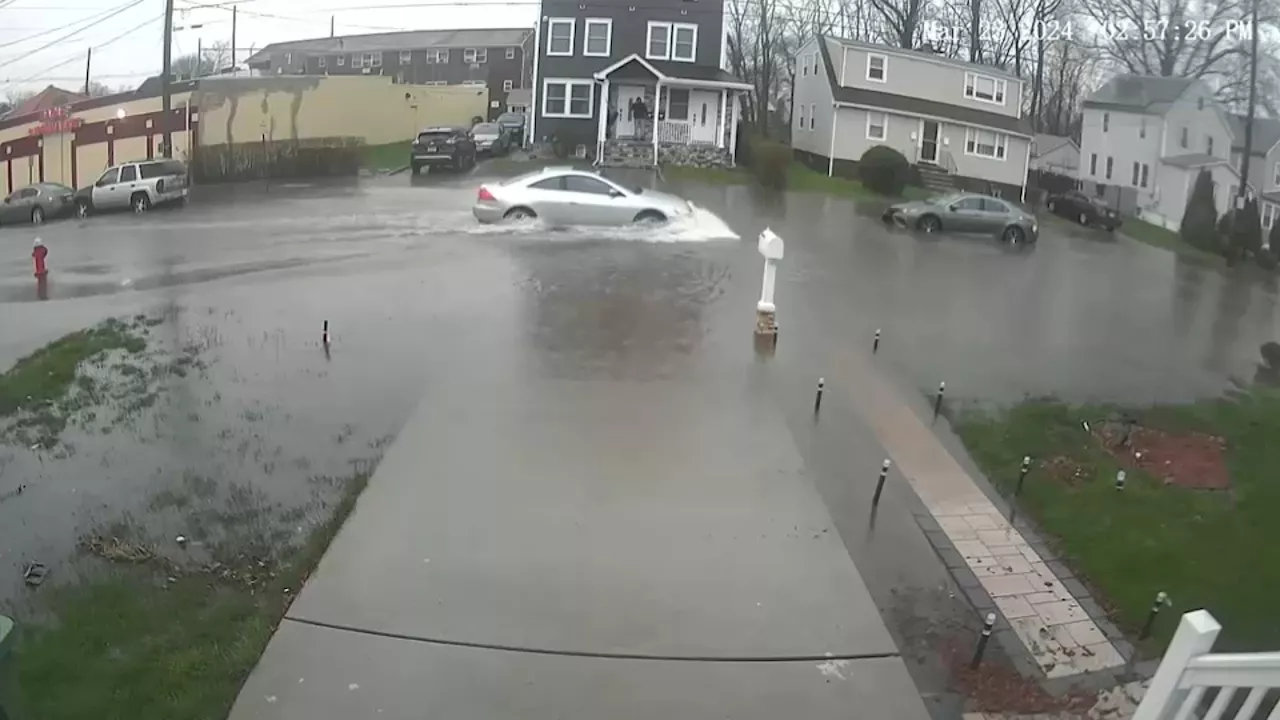
Tywan Mata, a first-time homeowner in Roselle, New Jersey, spent years navigating a bureaucratic nightmare after receiving conflicting flood-risk notices from FEMA. With the help of legal advocates, Mata eventually secured a total settlement of $14,273 after the agency initially denied his claims.
The $14,273 battle for Roselle's Tywan Mata
The financial instability faced by Tywan Mata began with a series of contradictory communications from the Federal Emergency Management Agency (FEMA). According to the report , a 2022 letter from FEMA informed Mata that his Roselle property sat within a special flood hazard area, making him eligible for a three-year Group Flood Insurance Policy funded by the agency. However, by 2024, a subsequent letter claimed the home was not in a hazard zone, which FEMA then used as the basis to deny a loss payment after a winter storm damaged the property.
The resolution of this dispute required the intervention of the legal advocacy group 7 On Your Side. By utilizing FEMA's own flood maps to prove the property's footprint was indeed in a risk zone, the advocates forced the agency to reverse its decision. This led to an initial payment of $5,495, followed by an additional $8,777 after a renewed appeal regarding uncovered repair invoices, bringing the final settlement to $14,273.
FEMA's 18-month mapping lag and the risk of false security
The struggle of Tywan Mata highlights a systemic vulnerability in how the United States tracks environmental risk.. As reported, FEMA confirmed that its flood-mapping process can take as long as 18 months to complete and is heavily dependent on the quality of local data provided to the agency. This delay means that the official maps used to determine insurance requirements and claim eligibility often lag significantly behind the actual conditions on the ground.
This discrepancy creates a dangerous environment for millions of Americans. When federal maps are outdated or incomplete, homeowners may believe they are safe from flooding when they are actually in high-risk zones. This "false security" often results in residents remaining uninsured, leaving them financially exposed when disaster strikes, as the official documentation fails to reflect the current reality of the landscape.
Susan Crawford's warning on outdated FEMA visualizations
The disconnect between official data and lived experience is a growing concern for climate experts. Susan Crawford,a climate-adaptation writer, argues that current FEMA visualizations are failing to incorporate recent flood events.. This suggests that the agency is relying on historical data that does not account for the increasing frequency and intensity of modern weather patterns, which are already causing repeated flooding across New Jersey.
For homeowners, this means that relying solely on a government letter may not be enough to ensure protection. The situation in Roselle suggests a broader trend where the burden of risk assessment is shifting from the federal government to the individual. Residents are increasingly encouraged to be vigilant and update their own risk assessments rather than trusting the static, often laggig, federal maps.
Who else in New Jersey is trapped by contradictory FEMA letters?
While Tywan Mata's case ended in a settlement, several critical questions remain unanswered. It is unclear how many other homeowners in New Jersey—or across the U .S.—have received contradictory hazard designations that led to denied claims. Furthermore, the source does not specify whether the errors in Mata's case were the result of a systemic software glitch in FEMA's mapping tools or isolated human error during the 18-month data processing window.
Additionally, there is no information on whether FEMA intends to audit other properties in the Roselle area to correct similar mapping errors proactively. Without a systemic review, other residents may only discover their mapping discrepancies after a disaster has already occurred and their claims are denied.
Comments 0