
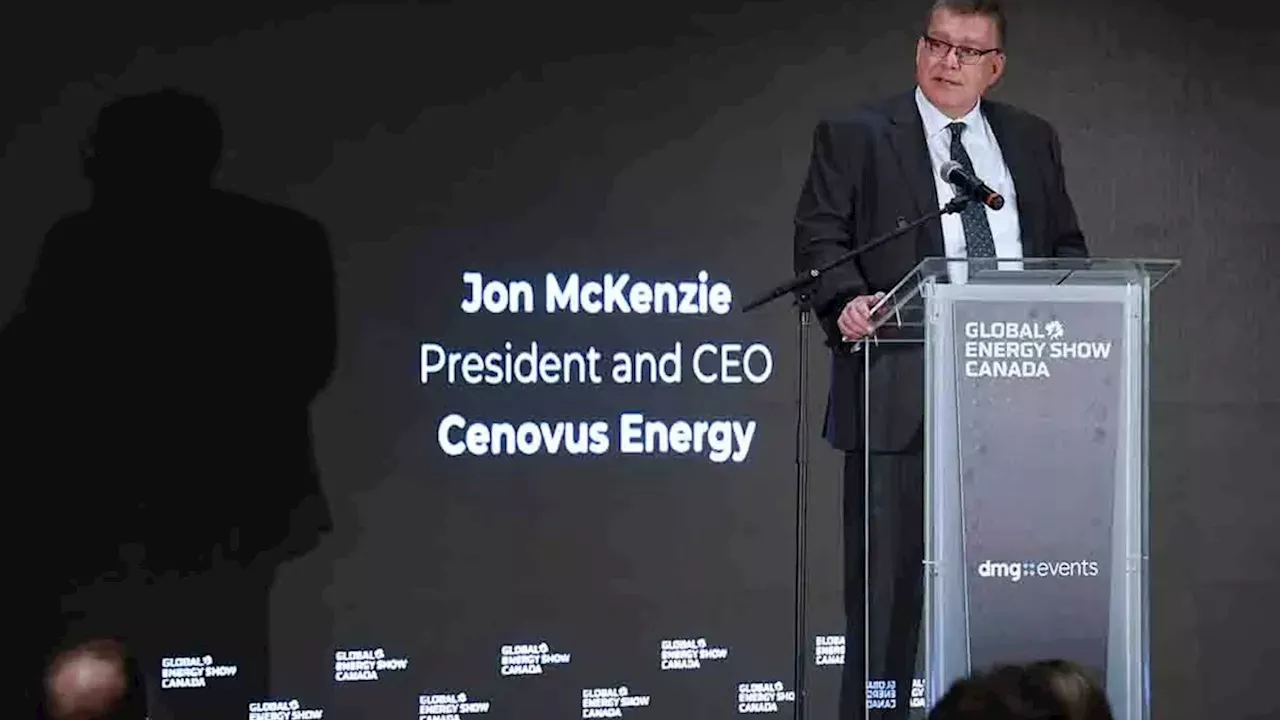
Cenovus Energy has announced a $5.7 billion agreement to purchase Athabasca Oilsands Ltd., a move designed to significantly increase its Canadian oilsand holdings. The deal, which includes a mix of cash and stock, is expected to add roughly 45,000 barrels of oil equivalent per day to the company's output.
A pattern of multi-billion dollar expansion since the 2017 ConocoPhillips deal
The acquisition of Athabasca Oilsands Ltd. is not an isolated event for Cenovus Energy, but rather the latest chapter in a long-term strategy of massive scale-ups. As the report indicates, this follows the $17.7 billion buyout of ConocoPhillips' interest in 2017 and the $8.6 billion purchase of MEG Energy in late 2025.. These moves suggest a leadership team focused on consolidating the Canadian energy landscape through high-value, long-term assets.
This aggressive growth strategy stands in contrast to the approach taken by Suncor, where CEO Rich Kruger has signaled a shift toward large-scale, low-intensity oilsand assets to improve the company's cost profile.. While Cenovus Energy is betting on sheer volume and resource depth, its competitors appear to be prioritizing operational efficiency and portfolio realignment.
Doubling inventory through the Leismer and Corner fields
By absorbing Athabasca Oilsands Ltd., Cenovus Energy effectively doubles its existing oilsand inventory. CEO Jon McKenzie noted that the deal provides access to the Leismer and Corner fields, which offer an estimated 75 years of proved and probable capacity. This long-term resource security is a cornerstone of the company's valuation.
The transaction also grants Cenovus Energy full ownership of Duvernay Energy Corp., adding another 45,000 barrels per day from shale feed to the company's production outlook for 2027. The purchase will be financed through a combination of cash and a stock offer set at $12 per share,a move intended to integrate these new, long-lived reserves into the existing Cenovus Energy infrastructure.
The climb toward a $5 billion net debt ceiling
The financial implications of this $5.7 billion package have created a divide among market observers. While the deal promises $85 million in annual synergies through asset consolidation and productivity gains, it also significantly alters the company's balance sheet.. According to the report, Cenovus Energy's net debt is projected to rise from approximately $3 billion at the end of Q3 to roughly $5 billion by the end of the year if the full cash payout is completed.
This financial pressure was reflected in the Toronto market, where Cenovus Energy shares initially fell by five percent before paring back to $44.59. Analysts such as Randy Ollenberger of BMO Capital Markets suggest the price is reasonable, provided the company can successfully manage its growth and debt-management trajectory. However,the rapid accumulation of leverage remains a primary concern for cautious investors.
Will regulatory reviews and shareholder votes delay the December close?
While the boards of both Cenovus Energy and Athabasca Oilsands Ltd. have signaled their approval, several hurdles remain before the deal is finalized. It is currently unclear how quickly regulatory reviews will proceed or if Athabasca Oilsands Ltd. shareholders will push for terms beyond the $12 per share stock offer. The transaction is expected to close in December, pending these critical approvals.
The broader energy landscape is also shifting as other players move into new territories. For instance, Ithaca Energy PLC saw its London shares rise by 3 percent following its acquisition of Cenovus Energy's Newfoundland stakes. This move allows Ithaca Energy PLC to become the operator of Terra Nova while retaining a minority interest in White Rose, demonstrating how Cenovus Energy's divestments are fueling the expansion of international competitors.
Comments 0