
On September 15, 2026, the International Civil Liberties Monitoring Group released a report detailing how Canadian organizations face sudden financial service restrictions. The document argues that current anti-terrorist financing frameworks lead to unjustified account closures for various non-profits.
Beyond isolated incidents: A systemic flaw in Canada's anti-terror laws
The International Civil Liberties Monitoring Group asserts that "de-banking" is not merely a collection of isolated commercial decisions by individual banks but a predictable result of Canada's anti-money-laundering and anti-terrorist-financing framework. As the report notes, the current regulatory environment creates a climate where banks prioritize risk avoidance over case-specific evidence.
This systemic issue echoes a 2026 study by Anver Emon, a law and history professor at the University of Toronto , which found that strict measures designed to prevent terrorist financing were already causing Muslim charities in Canada to withdraw humanitarian assistance from high-risk regions to protect their banking access. The new report suggests that this problem is embedded throughout the entire Canadian financial system rather than being confined to a single institution.
The humanitarian toll in Syria, Palestine, and Pakistan
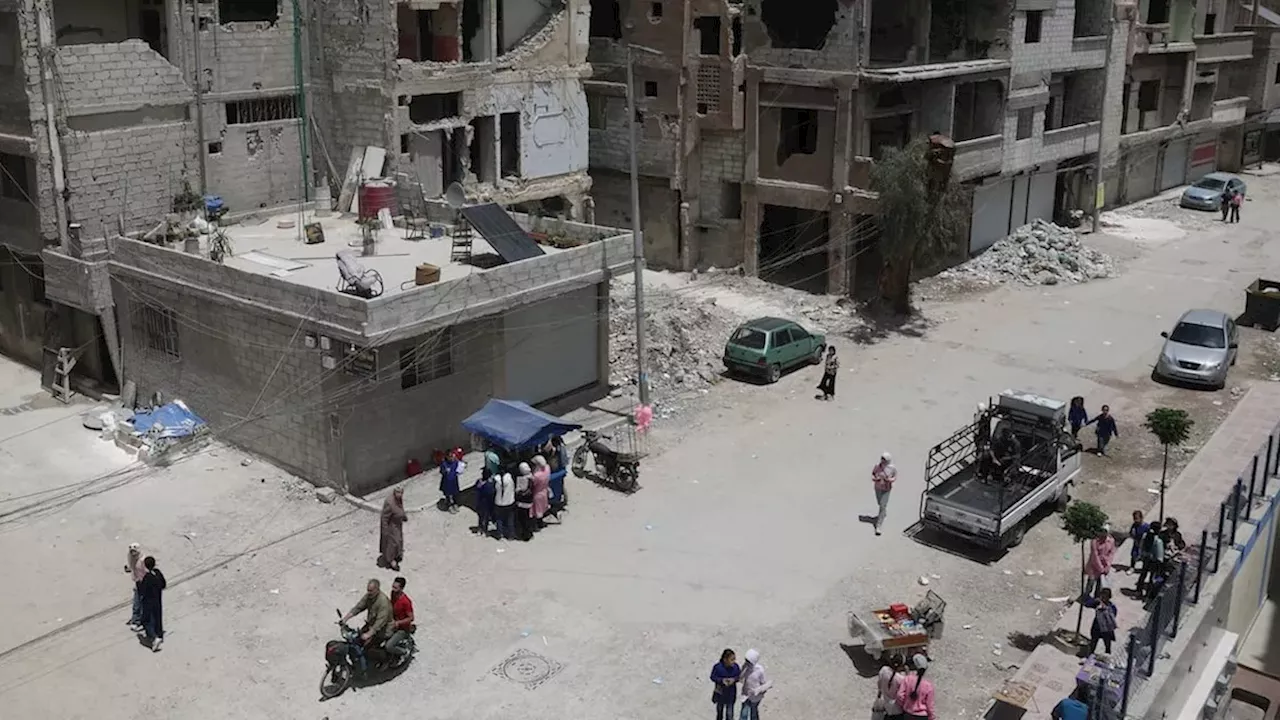
The report highlights how these financial restrictions disproportionately affect organizations working in jurisdictions such as Syria, Palestine, or Pakistan. Tim McSorley, the national coordinator for the monitoring group, stated that the consequences include millions of dollars intended for life-saving aid and international development being cut off.
Beyond the organizations themselves, the report notes that the practice can extend to the individual derisking of employees, board members, and even their families. this can cause lasting damage to professional reputations and personal livelihoods , even for those with no extremist involvement. The most affected groups include Muslim-led charities and international humanitarian non-governmental organizations.
The 15-day window and the lack of an appeal process
Because financial institutions in Canada are not legally required to provide specific reasons for closing an account, many organizations are left in the dark. According to the report, one large and established humanitarian organization operating in Syria was given only a 15 to 30-day window by a donation-processing platform before its services were terminated. The platform made this decision after its new banking partner flagged the organization as a deirsking concern.
In another instance , a charity's application for credit card services was initially welcomed by account managers, only for the account and related donation processing to be suspended without warning just one week later. These abrupt actions, which include exclusion from payment processors and interruptions to humanitarian programs, leave organizations unable to maintain essential services.
Who holds Canadian banks accountable for discriminatory closures?
Despite the scale of these closures, Canada currently lacks an independent body with a mandate to determine whether a derisking decision was reasonable, non-discriminatory, or supported by evidence. Furthermore, no authority systematically collects information regarding the scale or nature of de-banking across the country.
This leaves several critical questions unanswered : Which specific financial institutions are most responsible for these abrupt closures? How can the federal government ensure that the Finance Department and Public Safety Canada's policies do not inadvertently facilitate discrimination? And what specific transparency requirements are needed to prevent these "behind closed doors" decisions from crippling vital humanitarian aid?
Comments 0