
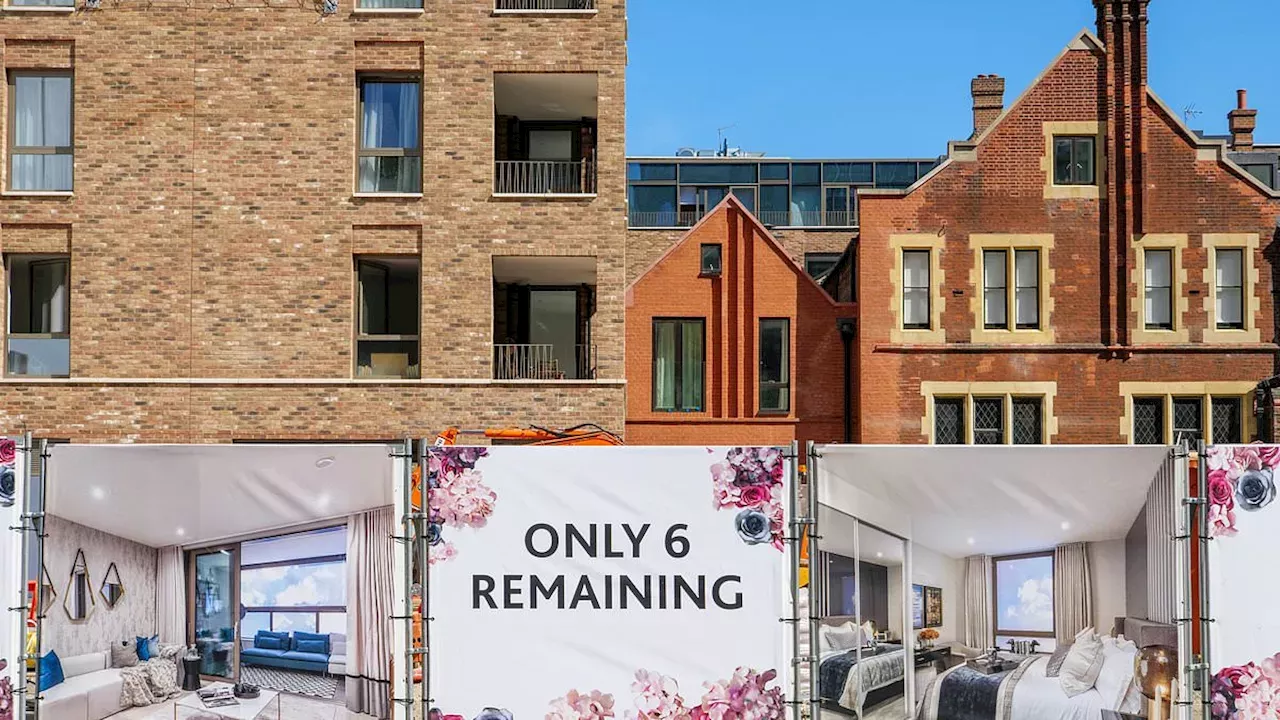
The UK government has launched the "Your First Home" scheme, offering first-time buyers a 2.5% deposit and a 20% equity loan. However, the program is strictly limited to new-build properties, a move designed to incentivize developers but one that critics fear will repeat the mistakes of its predecessor.
The £109 biillion shadow of the Help to Buy era
The "Your First Home" scheme serves as a direct successor to the Help to Buy program, which operated from 2013 until 2022. According to official figures from the Ministry of Housing, Communities and Local Government, the previous scheme facilitated the purchase of more than 387,000 properties, totaling approximately £109.2 billion in value.
While the program supported 328,000 first-time buyers, its effectiveness remains a point of contention. The Institute for Fiscal Studies (IFS) noted in April 2026 that the scheme's focus on new builds—which are often scarce in many regions—meant it had a limited impact on overall housing affordablity in England.
A 70.1% price surge for new-build properties
New-build homes currently command a significant financial premium over older properties in the UK. Data from HM Revenue & Customs indicates that new constructions average £396,889, while existing homes average £283,194, representing a 40.1% price gap.
The report suggests that government intervention may be exacerbating this disparity. Research from SAM Conveyancing estimated that the previous Help to Buy scheme inflated the prices of new-build properties by 70.1 per cent. This has led to concerns that injecting billions into the new-build sector through equity loans may create an artificial price bubble rather than making homes genuinely affordable .
Stagnant delivery at 152,791 annual completions
Despite government efforts to stimulate the market, housing supply has failed to return to previous highs. SAM Conveyancing reported that housing completions have stagnated at an average of 152,791 per year, a figure that sits well below the 2007 peak of 223,590 completions.
Andrew Boast, the chief executive of SAM Conveyancing, pointed out that current completion rates are running at less than half of the government's stated targets. this stagnation suggests that the strategy of using equity loans to drive demand for new builds has not yet successfully translated into a significant increase in construction activity.
The push to include existing homes in the scheme
The decision to restrict the "Your First Home" scheme to new-build properties has met with resistance from property experts. Mark Harris, chief executive of mortgage broker SPF Private Clients, noted that the government's strategy is specifically designed to encourage developers to build more homes to satisfy demand.
However, many are questioning why the UK Government has been less keen to provide help to those purchasing older, existing homes. It remains unclear whether the government will eventually expand the scheme to include the wider housing market or if the focus will remain exclusively on incentivizing developers through new-build mandates.
Comments 0