
A recent study by the retirement firm Standard Life indicates that individuals who delay their pension savings,termed "late bloomers," risk having £73,000 less at retirement than those who plan early. The research suggests that while the financial penalty for waiting is steep, proactive changes in later working years can still significantly improve a person's final financial position.
The £73,000 penalty for "late bloomers"
According to research from Standard Life, approximately one in four workers fall into the category of "late bloomers"—individuals who ignore retirement planning for a significant portion of their careers. The firm identifies three distinct saver personalities: the organized "planner," the passive "winger," and the "late bloomer" who attempts to rectify a lack of early saving.
The financial disparity is stark. Standard Life reports that late bloomers could end up with £73,000 less in their retirement funds compared to those who maintained consistent, early contributions. This gap highlights the compounding cost of delay, where missing the early years of growth creates a deficit that is difficult, though not impossible, to close.
Why an 8% early start beats a late 7% surge
The mathematical cost of waiting is illustrated by Standard Life's modeling of contribution rates. A worker who contributes 8% of their salary from the start of their career is projected to have a pension pot of approximately £347,000 by age 68. In contrast, a worker who pays the minimum 5% (with a 3% employer match) from age 22 to 50, and then increases their contribution to 7% at age 50, would only reach about £274,000.
Those who take an entirely passive approach, categorized as "wingers," face an even lower projected outcome of roughly £252,000. These figures demonstrate that while increasing contributions later in life helps, it rarely fully compensates for the lost growth of the first three decades of employment.
How David Gate blended defined benefit and contribution schemes
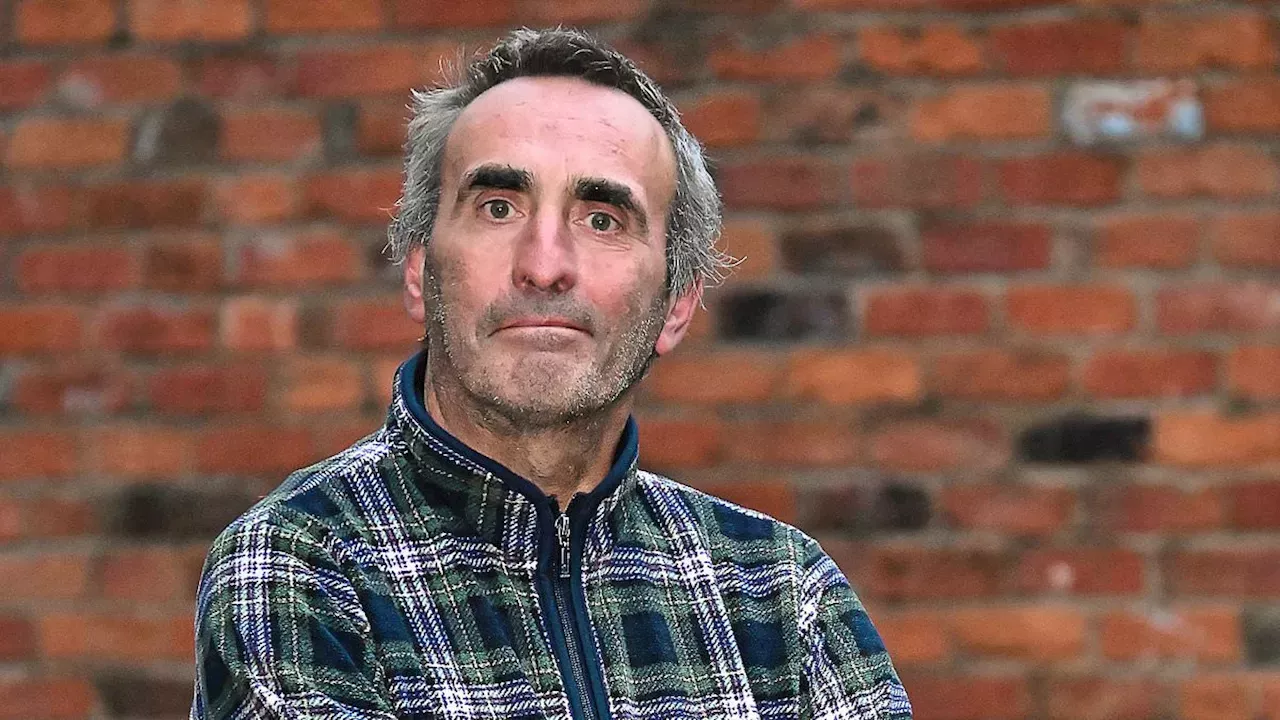
The case of David Gate serves as a practical example of how a late starter can diversify their income streams. after ignoring pensions in his 30s to prioritize a mortgage,David Gate began saving seriously at age 50. he utilized a defined benefit pension scheme during a tenure as a college teacher,which provides a guaranteed annual income that rises with inflation.
As reported by the source, David Gate later transitioned to a defined contribution pension through a production company, where the final sum depends on market growth and total contributions. Now 62, David Gate has accumulated a £90,000 defined contribution pot and expects £4,000 annually from his teaching pension, supplemented by the state pension at age 67.
The 2012 auto-enrolment shift for workers over 22
The struggle of late bloomers exists alongside a systemic shift in UK pension law. Since 2012, employers have been legally required to automatically enrol eligible workers—those aged 22 and over earning at least £10,000—into a pension scheme. Under these rules,the employer must contribute at least 3% and the employee at least 5%, with additional tax relief.
This legislative change was designed to prevent the rise of "wingers" by removing the friction of signing up. However, as David Gate's experience shows, auto-enrolment is a baseline rather than a complete strategy. For those who missed the boat before 2012 or worked in roles without schemes, the burden remains on the individual to maximize tax relief and increase voluntary contributions .
The missing data on tax relief and inflation volatility
While the Standard Life report emphasizes the importance of tax relief and inflation-linked pensions, it leaves several specific questions unanswered.. The source does not detail exactly how much the £73,000 gap is narrowed specifically by tax relief versus increased raw contributions, nor does it provide a breakdown of how different investment risk profiles affect the "late bloomer's" recovery path.
Furthermore, the report focuses heavily on the benefits of defined benefit schemes, but these are increasingly rare in the private sector. It remains unclear how a late bloomer entering the workforce today, without access to a guaranteed final salary pension, can realistically bridge the gap described in the research.
Comments 0