
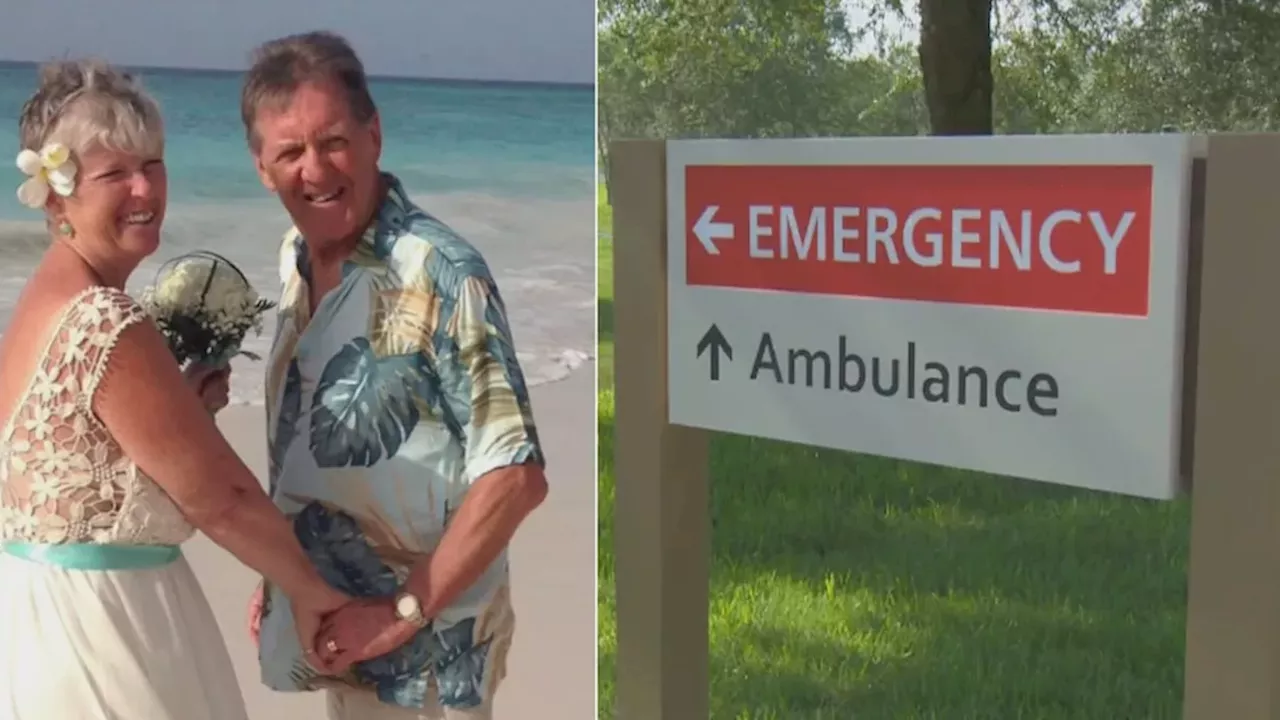
A couple from Collingwood, Ontario, is facing a $60,000 hospital bill after Manulife denied their travel insurance claim for a hip replacement in Barbados.. The insurer refused coverage based on the discovery of undisclosed pre-existing medical conditions.
The $60,000 hip replacement in Barbados
Doug Edwards and his wife, Carol Edwards, have visited Barbados for over three decades, always securing travel medical insurance for their trips.. During a visit this past March, Doug Edwards suffered a severe injury after tripping over a piece of concrete, resulting in a broken hip that required immediate surgical intervention.
Because of the intensity of the pain, Carol Edwards stated that the couple felt they had no choice but to proceed with a full hip replacement locally rather than attempting to return to Canada for treatment. The resulting medical expenses totaled $60,000, a sum the couple expected their Manulife policy to cover upon their return home.
Why Manulife flagged degenerative arthrosis and low bone mass
According to a report by CTV News, Manulife denied the $60,000 claim after a review of Doug Edwards' medical history revealed discrepancies in the insurance application. The insurer's findings indicated that Mr. Edwards had previously undergone a right hip replacement and suffered from "mild left hip degenerative arthrosis and low bone mass," as well as reported left hip pain associated with a limp.
In a statement to CTV News, a Manulife spokesperson emphasized that acurate and complete answers on medical applications are essential, noting that incomplete information can jeopardize the validity of the entire policy. The company suggested that customers who are uncertain about medical questionnaires should consult licensed travel insurance agents to ensure all required information is disclosed.
Martin Firestone's warning on the "number one reason" for claim denials
The dispute between the Edwards family and Manulife reflects a common friction point in the travel insurance industry.. martin Firestone, president of Travel Secure Inc., told CTV News that non-disclosure is the primary reason insurance claims are denied. he noted that when a claim is filed, insurers routinely order detailed doctor reports to verify the claimant's medical history against their application.
This process often catches travelers who may not realize that a chronic condition or a past surgery—even one they consider "resolved"—must be explicitly listed. For many Canadians , the low cost of travel insurance creates a false sense of security, while the actual payout depends on a rigorous clinical audit of the policyholder's health records.
Did the Edwards' application explicitly omit the right hip replacement?
While Manulife has pointed to the medical records as the basis for the denial, a key detail remains unverified: whether the Collingwood couple intentionally omitted these conditions or simply misunderstood the scope of the questions asked. The source reporting does not include a detailed response from the Edwards regarding the specific medical findings cited by Manulife, only Carol Edwards' assertion that the couple should be reimbursed after their ordeal.
Furthermore, it is unclear if the couple sought professional guidance from an agent during the application process,a step Manulife recommends to avoid such costly misunderstandings. Without the specific wording of the application and the couple's answers, the case remains a stalemate between a corporate policy and a personal medical crisis.
Comments 0