
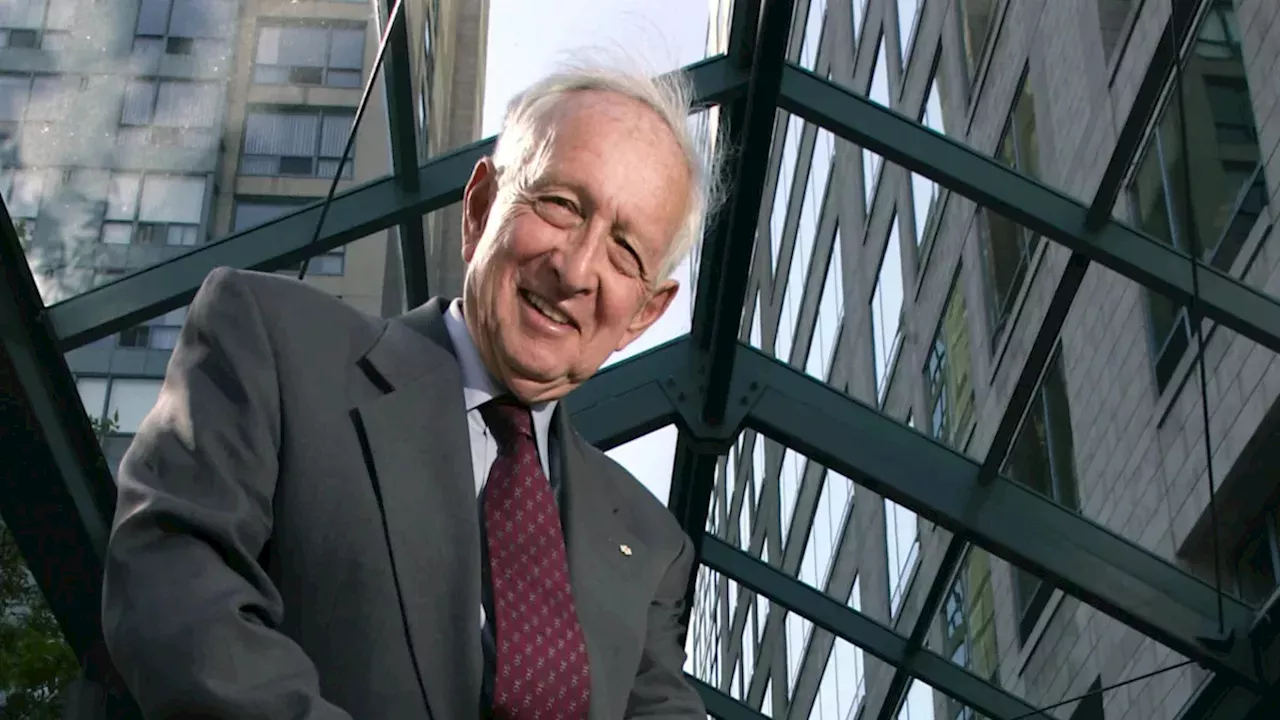
Stephen Jarislowsky,a legendary Montreal-based investor, passed away on October 8 at the age of 101. He is remembered for transforming a modest $150 starting sum into a financial powerhouse managing $40 billion in assets.
From $150 to a $40-billion Montreal Empire
Stephen Jarislowsky began his career in Berlin in 1925 before establishing Jarislowsky Fraser & Co. in Montreal. According to the report, the firm was launched with just $100 of Jarislowsky's own money and $50 from a partnr. Over several decades, this small venture evolved into one of Canada's most respected investment firms, managing massive portfolios for wealthy families, foundations, and pension funds.
The scale of the operation eventually attracted major institutional interest. In 2018, Scotiabank acquired Jarislowsky Fraser & Co. for $950 million. This acquisition marked the transition of a boutique, quality-focused philosophy into the fold of one of Canada's largest banking institutions, cementing Jarislowsky's status as a titan of the Canadian financial landscape.
The 5% to 6% Real Return Benchmark
While modern retail traders often chase explosive,overnight gains, Stephen Jarislowsky operated on a much more disciplined timeline. As reported, Jarislowsky expected stocks to generate an average real return of 5% to 6% annually. He believed this modest but consistent growth, paired with the power of compounding, was sufficient to build immense wealth over a professional lifetime.
His strategy relied on identifying high-quality companies with strong management teams and a proven track record of doubling their earnings every five to seven years.. Rather than attempting to time the market or following "hot tips," Jarislowsky focused on the fundamental health of the businesses he owned, holding them for decades to maximize the effect of compound growth.
Why a 2% MER is a Red Flag
A central pillar of the Jarislowsky philosophy was the aggressive minimization of costs. He warned investors against paying high fees for "pedestrian results," a sentiment echoed by data from the SPIVA Canada Scorecard by S&P Dow Jones Indices. The report notes that high management expense ratios (MERs) can significantly erode long-term wealth.
To illustrate this, Saskatchewan's Financial and Consumer Affairs Authority (FCAA) points out that on a 5% annual return over 25 years, a 1% fee can drastically reduce the final portfolio value. For the modern DIY investor, Jarislowsky's approach suggests that any fund with an MER near 2% warrants a critical review and potential replacement with lower-cost alternatives, such as exchange-traded funds (ETFs).
The Gap Between Institutional Access and DIY Portfolios
It is important to distinguish between the tools available to Stephen Jarislowsky and those available to the average retail investor. Jarislowsky utilized a professional research team and maintained direct access to corporate executives to vet the quality of his investments. Most individual investors lack this infrastructure, meaning a concentrated portfolio of a few stocks carries significantly higher risk than a diversified fund.
This disparity suggests that while Jarislowsky's principles of patience and fee-control are universal, his specific method of stock picking is difficult to replicate without institutional resources. For those in their peak earning years or younger investors, the core lesson remains the importance of time and automation via TFSA and RRSP contributions, rather than attempting to mimic the concentrated bets of a billionaire.
The Unseen Details of the $950 Million Scotiabank Deal
Despite the detailed account of his philosophy, several questions remain regarding the institutionalization of his legacy. The source mentions the $950 million sale to Scotiabank in 2018, but it does not disclose the specific terms of the deal or how Scotiabank has maintained the "patient" investment style within a large corporate banking structure.
Furthermore, while the report highlights Jarislowsky's success, it does not provide a comparative analysis of how his specific quality-focused holdings performed against broader benchmarks like the S&P/TSX Composite Index over the final decade of his life. These missing details leave a gap in understanding whether his "boring" approach continued to outperform in the era of high-frequency trading and AI-driven markets.
Comments 0