
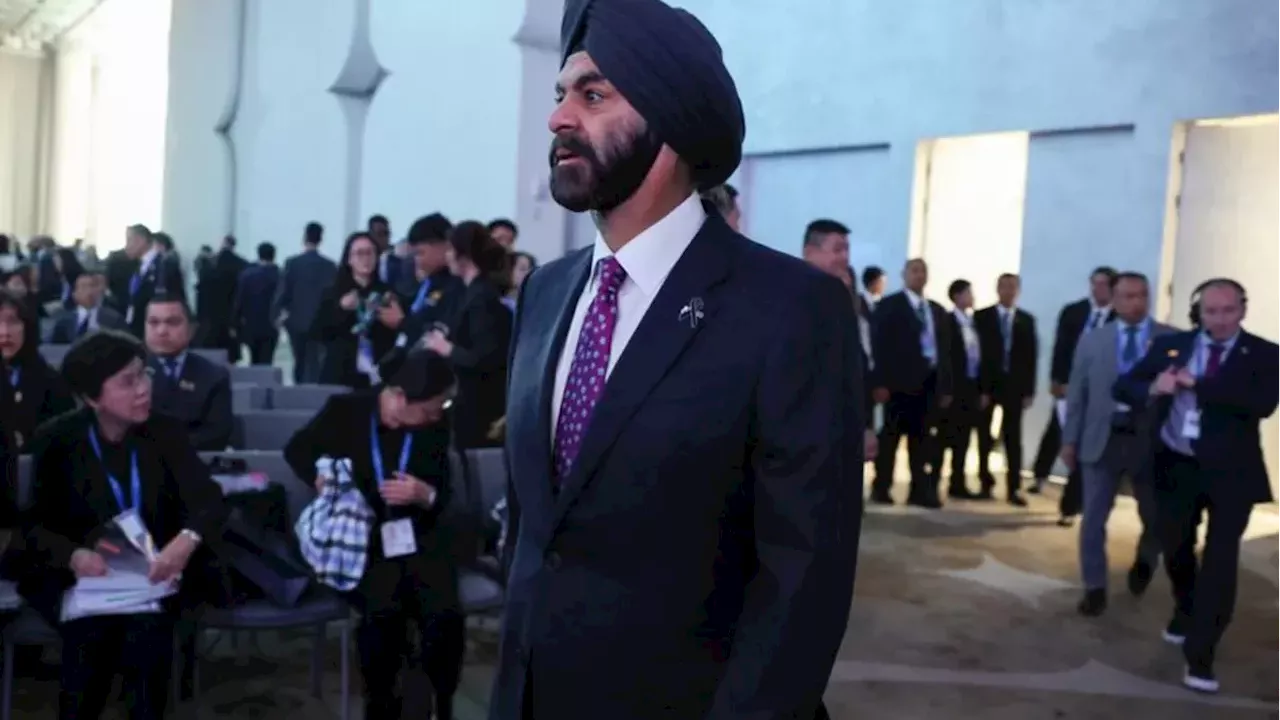
At the IMF and World Bank Annual Meetings in Bangkok on October 16, 2026, President Ajay Banga unveiled a plan to quintuple the World Bank's critical minerals financing. The initiative seeks to raise the budget for essential mineral projects to $19 billion for the 2026–2030 period.
A five-fold jump to $19 billion in financing
The World Bank Group is dramatically scaling up its investment in the materials necessary for the global energy transition. According to the report, the bank's new Metals and Minerals Implementation Plan (MMIP) targets $19 billion between 2026 and 2030, a massive leap from the $3.6 billion allocated during the 2021–2025 cycle. This capital is intended to support the extraction and processing of lithium, nickel, cobalt, gallium, and rare-earth elements .
This massive influx follows a highly successful 2026 fiscal year, during which the bank mobilized $112 billion in private capital—more than triple the amount seen in 2022. By increasing its financial footprint, the World Bank aims to stabilize the markets for these essential elements while addressing the growing demand from the technology and automotive sectors .
Building local value chains through 20-country compacts
To ensure that mineral wealth benefits more than just end-users, the World Bank has launched "critical minerals compacts" with several multilateral development banks. These agreements are designed to foster local value chains within the 20 partner countries identified by President Ajay Banga. The goal is to move beyond simple extraction and toward local processing, which creates jobs and keeps economic gains within the source nations.
By focusing on these compacts, the World Bank intends to strengthen global supply chains against geopolitical volatility while promoting social and environmental safeguards. This approach addresses long-standing criticisms of the mining industry, where raw materials are often exported with little local economic benefit.
Stephen Bessent and the U.S. push for deep-sea mining
The United States, acting as the World Bank's largest shareholder, is exerting significant influence on the direction of this new funding. As reported in the briefing, U.S. Treasury Secretary Stephen Bessent has called for the bank to play a more active role in de-risking the industry and improving infrastructure. Notably, the U.S. is also looking toward the potential of deep-sea mining ventures to secure the next generation of tech materials.
While the World Bank has not explicitly committed to deep-sea extraction, President Banga has signaled a "precautionary approach" to the sector. The bank maintains that any engagement in such nascent industries must strictly comply with existing sustainability criteria and environmental policies.
Which 20 countries will lead the transition?
Despite the scale of the announcement, several critical details remain unverified. While the bank has identified 20 countries for its new partnership model, the specific names of these nations have not been disclosed in the Bangkok announcement. This leaves investors and policymakers wondering which specific regions will become the primary beneficaries of the $19 billion influx.
Furthermore, the tension between the U.S. desire for deep-sea mining and the World Bank's "precautionary approach" remains a significant point of friction. It is currently unclear how the bank will balance the Treasury Secretary's calls for expansion with its own commitment to environmental safeguards in unexplored maritime territories.
Comments 0