
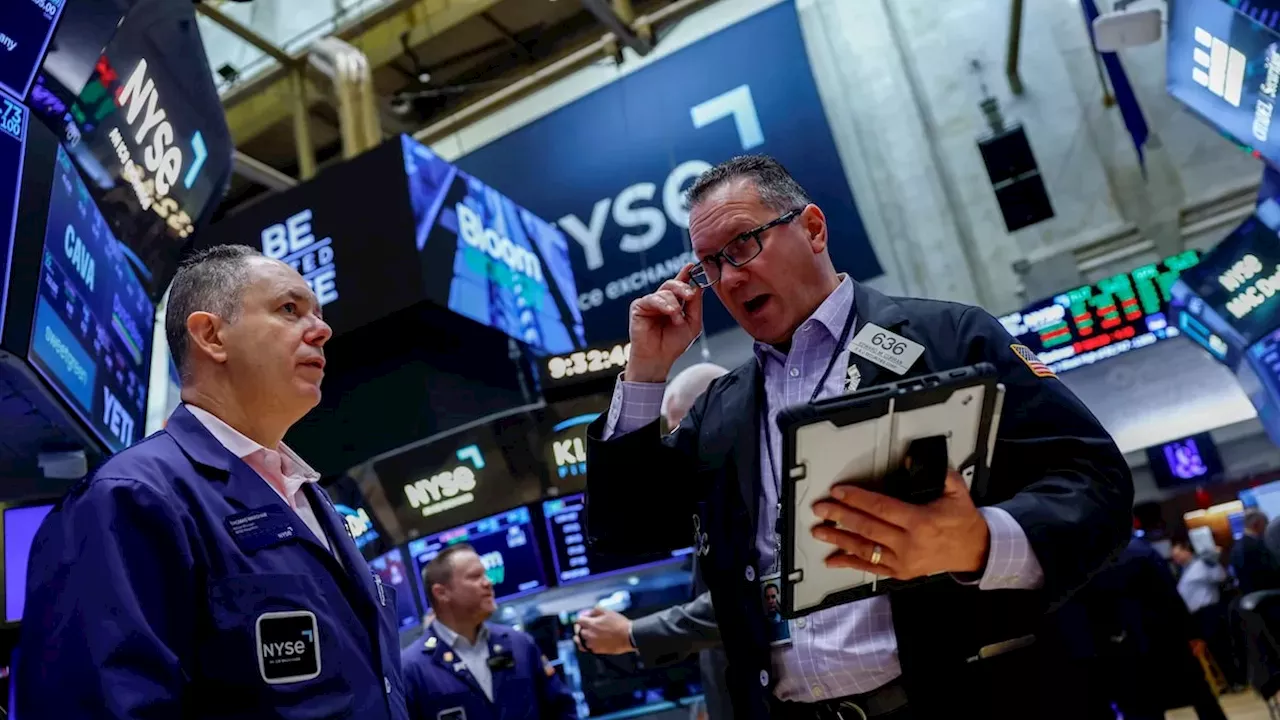
Global financial markets are currently in a holding pattern as investors await significant corporate earnings reports. Meanwhile, rising tensions in the Middle East have pushed oil prices higher, even as the Canadian dollar shows strength against the US dollar.
Meta’s Muse assistant and the high cost of AI adoption
Wall Street is currently navigating a high-stakes earnings season that could dictate market direction for the coming quarter. Markets are bracing for a heavy-hitting roster of corporate results, including Meta Platforms Inc., Tesla Inc., International Business Machines Corp. (IBM), AT&T Inc., and Philip Morris International Inc. This period of uncertainty is reflected in mixed Wall Street futures, where the Dow remains in the red while investors also look toward Thermo Fisher Scientific Inc., Texas Instruments Inc., NextEra Energy Inc., and CSX Corp.
The focus on Meta Platforms Inc. is particularly acute as the market seeks validation for massive tech expenditures. as reported by the wire service, Ipek Ozkardeskaya, a senior analyst at Swissquote, noted that investors are looking for evidence that the company's spending on its Muse assistant and advertising growth can justify its recent capital outlays. This reflects a broader trend where the initial excitement over artificial intelligence is being replaced by a demand for tangible, bottom-line results .
The climb toward $110 Brent crude amid geopolitical friction
Energy markets are reacting sharply to the instability in the Middle East and the ongoing Russia-Ukraine war. Brent crude futures have surged to US$110.20 a barrel, while West Texas Intermediate (WTI) has climbed to US$99.15. This volatility is part of a larger pattern where geopolitical risk premiums are being priced into commodities,even as falling U.S. crude and product inventories provide some additional support to the market.
While overseas markets show mixed results—with the Germany DAX rising 0.17 per cent and the Hong Kong Hang Seng falling 0.9 per cent—the energy sector remains dominated by fear. PVM analysts suggested that while traders are acting on a bullish bias, the long-term justification for these price levels remains debatable because neither of the two primary geopolitical conflicts shows any signs of de-escalation.
A strengthening Loonie and the 5.120% US 10-year yield
While equities and commodities face volatility, the currency and bond markets are showing distinct movements. The Canadian dollar has strengthened, trading at approximately $1.4054 per US$1, up about 0.36 per cent against the greenback over the last month. This movement occurs alongside a rise in the U.S. 10-year note yield, which has reached 5.120 per cent.
The broader U.S. dollar index has also seen a slight uptick to 101.79, even as the euro slipped to US$1.1221 and the British pound climbed to US$1.3395. these shifts highlight a complex tug-of-war between strengthening domestic currencies and the rising cost of debt in the United States.
What the upcoming UK inflation and Japan trade data will reveal
Several critical data points remain unverified or pending,leaving market participants in a state of cautious anticipation. One major question is whether the current surge in oil prices is a temporary reaction to supply fears or a sustained trend, as the current reporting does not confirm if any actual supply disruptions have occurred or are merely speculative.
According to the report from Reuters and The Canadian Press, the market is also waiting to see how upcoming economic releases, such as the UK inflation figures for September and Japan's September trade balance, will influence central bank policies. These pending figures will be essential in determining if the current strength in the Canadian dollar and the rise in U.S. bond yields are part of a larger, more permanent economic shift.
Comments 0