
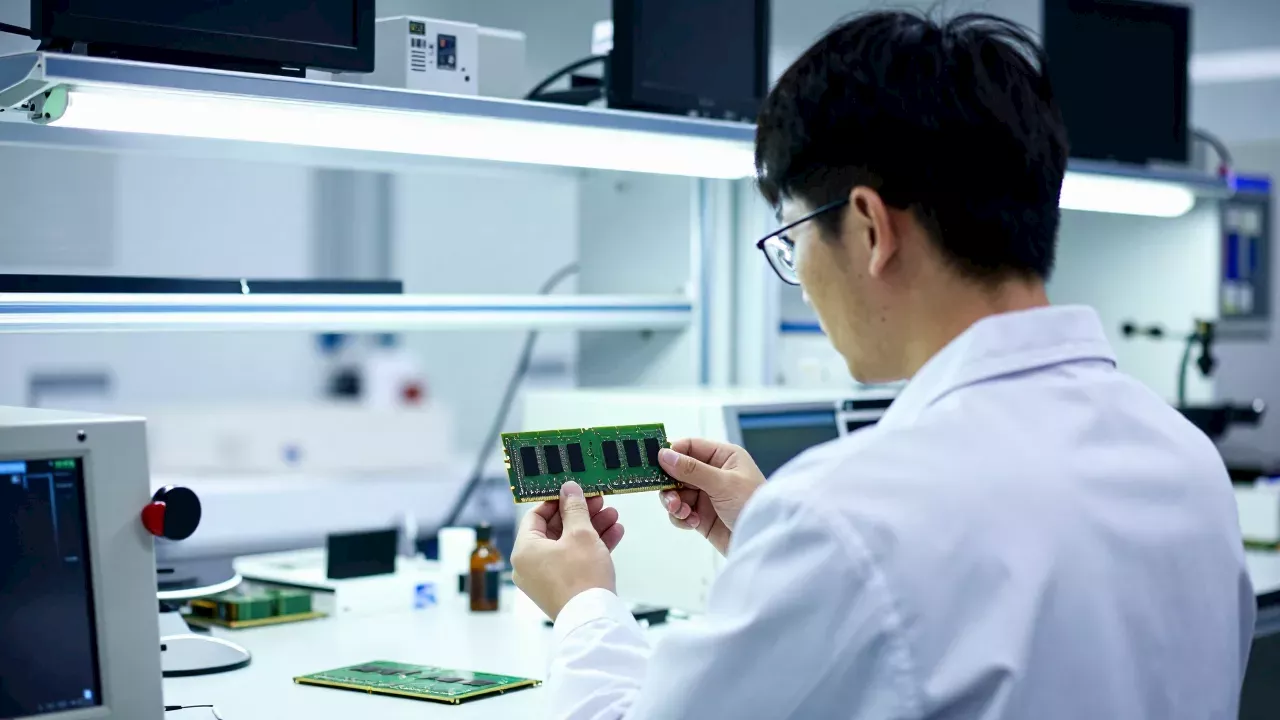
Micron Technology has delivered a powerful fourth-quarter performance, surpassing analyst projections for both revenue and earnings per share. This growth is fueled by an unprecedented surge in demand for memory components within the artificial intelligence sector.
Beating the $51.49 billion revenue consensus
Micron Technology's fourth-quarter results significantly outperformed the consensus estimates provided by market analysts.. According to the report, the company posted an earnings per share of $33.42, which was a notable jump from the expected $31.83. Revenue also exceeded expectations, reaching $54.23 billion compared to the $51.49 billion forecast.
The scale of this growth is evident when comparing the current figures to the previous year .. The company saw its revenue skyrocket from $11.31 billion to $54.23 billion, a testament to the shifting landscape of the semiconductor industry. This massive year-over-year climb highlights the rapid acceleration of the memory market as computing needs evolve.
A $10 billion commitment to 200-mm manufacturing
The company is embarking on a massive $10 billion manufacturing expansion to secure its future market position. This decade-long investment is aimed at constructing a new fabrication facility that will utilize a 200-mm manufacturing line. by expanding this capacity, Micron aims to ramp up the production of specialized hardware, including:
- Next-generation DRAM
- High-performance flash storage
This strategic move is intended to ensure the company can meet the specialized requirements of the growing enterprise and AI-driven storage markets, positioning Micron as a primary supplier for the next decade of hardware development.
The AI-driven surge in high-bandwidth memory demand
The explosive growth in artificial intelligence is the primary catalyst for Micron's recent financial success. Specifically, the demand from data centers for high-bandwidth memory (HBM) used in AI processors and graphics cards has become a dominant market force. This momentum is reflected in the company's stock performance, which has seen a 275 percent increase year-to-date and a 550 percent surge over the last twelve months.
Looking ahead, Micron has raised its second-quarter revenue guidance to a range of $60 billion to $63 billion. This projection sits significantly higher than the $57 billion estimate previously held by analysts, signaling that the company expects the AI-driven tailwinds to continue unabated into the next quarter.
Will Apple and consumer brands absorb rising memory costs?
Rising memory costs are creating a difficult economic landscape for consumer electronics manufacturers like Apple. As the price of essential components climbs, these companies face a choice between protecting their profit margins or maintaining high unit sales . The report suggests that some manufacturers have already begun increasing device prices to offset these costs.
This trend raises a critical question for the broader technology ecosystem:how much of the AI-driven memory premium can the average consumer actually tolerate before demand for high-end electronics begins to falter? While the enterprise sector is currently thriving, the industry must still navigate the trade-off between high-performance hardware and consumer affordability.
Comments 0