
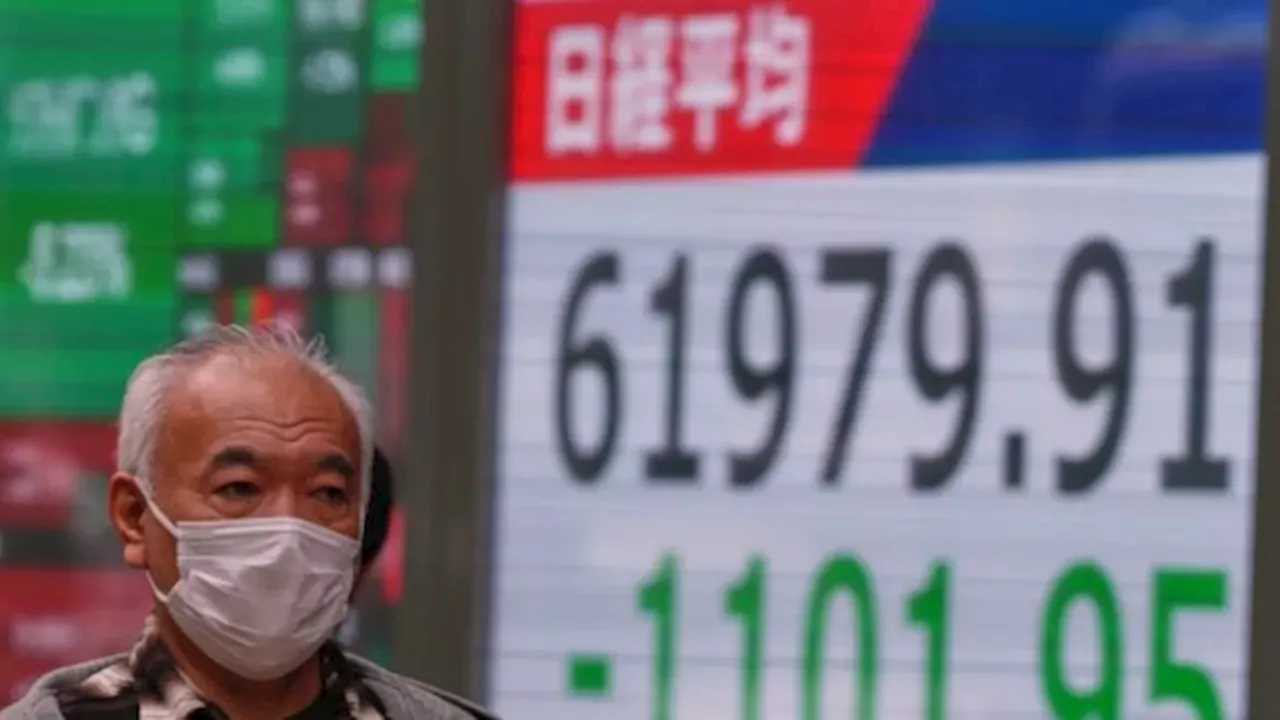
Global equity markets rose following US midterm elections that resulted in a divided government, with Democrats securing majorities in both the House and Senate. This political split has provided a sense of stability for investors, who generally prefer the predictability of legislative gridlock over sweeping policy shifts.
The "Stability of Stalemate" in Washington
The recent US midterm election results have triggered a broad rally as investors react to a likely period of legislative gridlock. As reported by the source, the S&P 500 rose 0.2% and the Dow Jones Industrial Average increased by 0.4% in response to the news that Democrats would hold majorities in both the House of Representatives and the Senate.
Market participants generally view a split government as a safeguard against radical economic restructuring . According to Stephen Brown of Capital Economics, the magnitude of the Democratic gains is unlikely to trigger immediate, sweeping changes because the party lacks a filibuster-proof majority in the Senate, and President Trump retains the power to veto significant legislation. This anticipated deadlock is seen as a way to reduce uncertainty for corporate earnings and long-term economic planning.
Apple’s margin squeeze and the rising cost of AI memory
While the broader market finds comfort in political stability, the technology sector is grappling with the uneven costs of the artificial intelligence boom. Apple is currently facing unique pressures; the company expects to see lower profit margins for every $1 of revenue generated during the final three months of this year due to the rising cost of computer memory chips. these price hikes are being driven by the intense demand for hardware required to build massive AI data centers.
This cost volatility is creating a divergent landscape for tech giants. While heavyweights like Microsoft, Amazon, and Meta Platforms all saw gains of more than 2% driven by AI infrastructure spending, other players are struggling. In Asian markets, SoftBank Group shares fell 3.2%, and Japanese chipmaker Kioxia Holdings tumbled 5.4% after missing market expectations for the October-December period.
European gains and Australia's rate-driven dip
International trading floors have largely aligned with the optimism seen in the United States. In early European sessions, the CAC 40 in Paris rose 0.4% to 8,055.02, Germany's DAX climbed 0.5% to 25,995.13, and Britain's FTSE 100 edged up 0.1% to 10,646.43. These movements suggest that global investors are pricing in the expected stability of a divided US legislature.
However, the global rally has not been uniform across all regions. australia's S&P/ASX 200 fell 0.6% to 8,834.50 following a decision by the Australian central bank to raise interest rates on Tuesday. this serves as a reminder that while political news may buoy equities, local monetary policy remains a potent force for market volatility.
The looming Bank of England and Eurozone inflation data
Significant macroeconomic uncertainty remains regarding the future of inflation and interest rates. Investors are currently looking toward two major upcoming events to determine if the current rally can be sustained: the release of the eurozone's flash consumer price index for October and the Bank of England's upcoming interest rate decision. Until these figures are released, the true direction of global markets remains unverified, as traders weigh the impact of potential central bank tightening against the current political stability.
Comments 0