
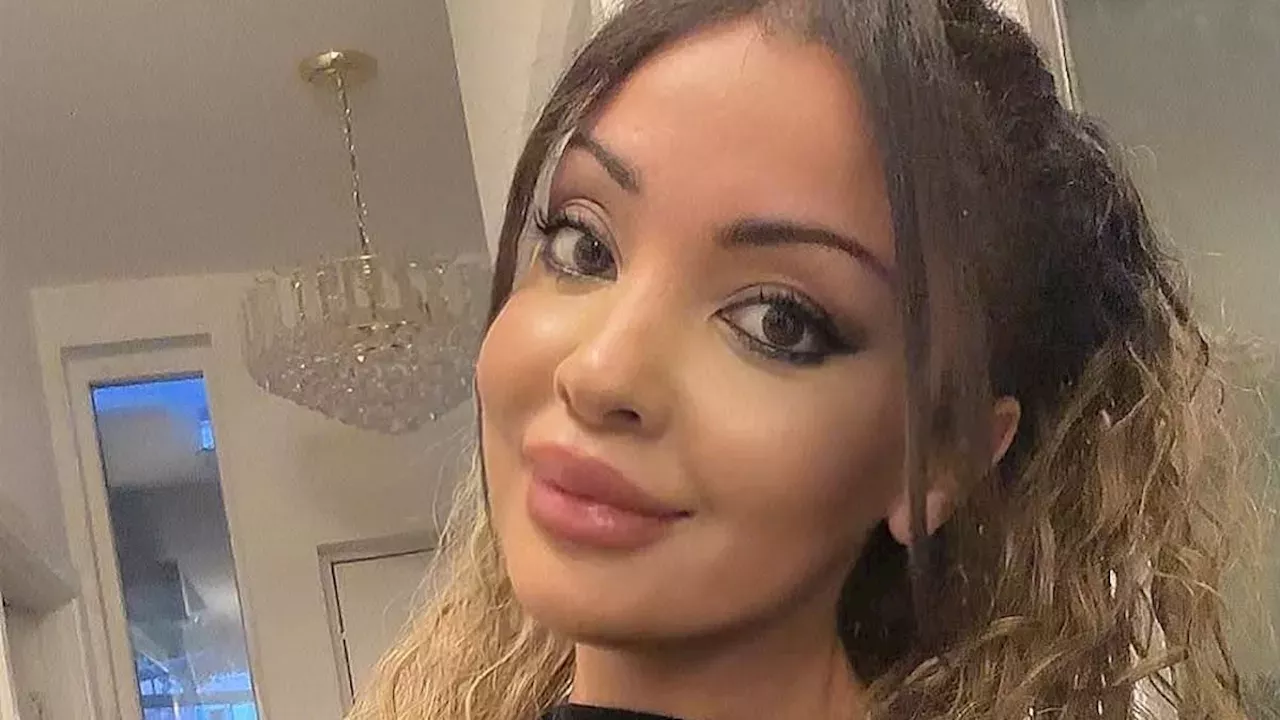
Charlene Woracker, a mother of four from Sheffield, successfully eliminated £12,000 in personal debt over the course of a single year. She achieved this financial recovery by replacing professional grooming services with DIY alternatives and implementing a rigorous spending freeze.
The 33% interest rate and the cycle of borrowing
The financial crisis for Charlene Woracker began following her separation from the father of her children, which left her without a steady income. To survive, Woracker relied on a combination of catalogue debts, "buy now, pay later" schemes, and credit cards. According to the report, one specific credit card carried an interest rate of 33%, a figure that made it nearly impossible to reduce the principal balance through minimum payments alone.
This debt spiral took a significant psychological toll on the 35-year-old Sheffield resident. Woracker suffered from panic attackks and insomnia as she watched her balances climb. The report notes that high credit limits further complicated the situation, making it easy for Woracker to overspend on household items and clothing while attempting to maintain a standard of living for her four children, aged three to seventeen.
Using ChatGPT to replace £150 in monthly beauty costs
The turning point for Charlene Woracker involved a total overhaul of her personal grooming expenses. Before her transition to DIY, Woracker spent roughly £50 a month on makeup and between £150 and £250 per visit for salon services, including hair coloring and extensions. By utilizing ChatGPT to source homemade beauty recipes, she was able to replace expensive products with household items, such as using cocoa powder to create her own bronzer.
Beyond makeup, Woracker taught herself the technical skills required to cut, dye, and apply hair extensions to her own hair. As reported, this shift to becoming her own beautician and hairdresser saved her approximately £150 every month. These savings, combined with the cancellation of unnecessary subscriptions and meticulous meal planning, were funneled directly into her debt repayments.
The precariousnses of "Buy Now, Pay Later" for single parents
The experience of Charlene Woracker reflects a broader, systemic trend in the UK where "buy now,pay later" (BNPL) services and high-interest catalogue credit are marketed as accessible liquidity for those without traditional income.. For single parents in precarious financial positions, these tools often transform from temporary bridges into permanent debt traps. Woracker's struggle highlights how the ease of accessing credit can mask the long-term cost of borrowing when interest rates reach the levels she encountered.
This case also underscores a growing movement of "extreme budgeting" driven by the cost-of-living crisis. By sacrificing social outings, takeaways, and small treats for an entire year, Woracker prioritized the long-term security of her children over immediate gratification. Her journey suggests that for some, the only way out of high-interest debt is a total withdrawal from consumerist habits.
Which creditors accepted Woracker's negotiated settlements?
While the report confirms that Charlene Woracker negotiated settlements with her creditors to accelerate her debt clearance, it does not specify which financial institutions or catalogue companies agreed to these terms. It remains unclear whether these creditors accepted partial payments as full satisfaction of the debt or if they agreed to freeze interest rates to facilitate her repayments.
Additionally, the report mentions that Woracker now shares her money-saving tips online, but it does not name the specific platforms or communities where she provides this advocacy. there is also no detail on the long-term sustainability of her DIY beauty methods or whether the cost of the raw materials used in her AI-generated recipes provides a permanent saving over professional products.
Comments 0