
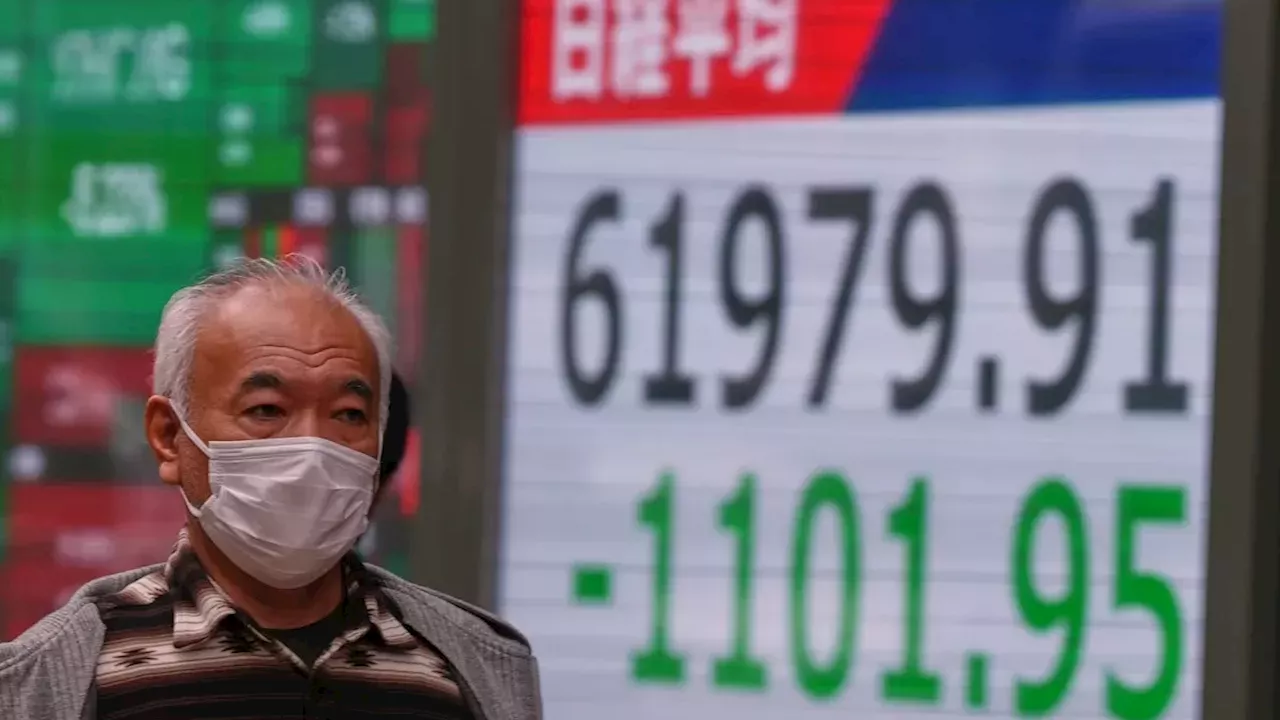
Global markets reacted with mixed volatility on November 4, 2026, after Democrats won control of both U.S. congressional chambers.. While Asian indices largely climbed, U.S. stocks split along the lines of artificial intelligence exposure and political expectations.
The Trump Veto and the Democratic Congressional Majority
The U.S. midterm elections resulted in significant Democratic majorities in both the House and Senate, yet investors are treating this shift as a stabilizing force rather than a catalyst for upheaval. According to the report, global financial institutions generally prefer a divided government because it prevents the kind of drastic regulatory overhauls that can destabilize the economy.
Stephen Brown, an economist at Capital Economics, noted that the Democratic Party still lacks a filibuster-proof majority in the Senate, which severely limits their ability to pass legislation unilaterally. Furthermore, President Trump retains the veto power to block most congressional initiatives. This constitutional gridlock suggests that sweeping economic changes are unlikely to materialize quickly, reducing the risk of abrupt fiscal shocks for multinational corporations.
Hang Seng and Shanghai Gains vs. SoftBank's 3.2% Slide
In Asia,the Hang Seng Index in Hong Kong rose 1.1 percent to 23,791.61 points, while China's Shanghai Composite Index jumped 2.2 percent to 3,686.17 points. South Korea's Kospi index also saw a modest increase of 0.6 percent, closing at 5,683.80 points. These gains suggest a level of cautious optimism in the East despite the political shifts in Washington.
However, the rally was not universal. Australia's S&P/ASX 200 fell 0.6 percent to 8,834 .50 points, a decline attributed to the Australian central bank's decision to raise interest rates on Tuesday. Additionally, SoftBank Group, a major investor in OpenAI, saw its shares drop 3.2 percent as investors recalibrated their risk exposure to artificial intelligence ventures.
Nvidia's Surge and Apple's Memory Chip Margin Squeeze
The U.S. equity markets displayed a sharp divergence based on AI utility, with the Nasdaq Composite climbing 0.8 percent while the Dow Jones Industrial Average dropped 197 points. As reported, chipmakers Nvidia and Broadcom were the primary drivers pushing the S&P 500 upward, reflecting sustained confidence in the hardware necessary for AI development. Other infrastructure giants, including Microsoft, Amazon, and Meta Platforms, all saw gains of more than 2 percent.
In contrast, Apple faced significant headwinds. While Apple is a Big Tech leader, the company is less dependent on AI than its peers and is now suffering from the "AI tax." The rush to build AI data centers has driven up the cost of memory chips, which are essential components for Apple's hardware. Apple stated that it expects to generate less profit from each dollar of revenue during the final quarter of the year due to these rising component costs.
The 4.96% Treasury Yield and DuPont's 8.6% Rally
Macroeconomic pressures mounted as the yield on the 10-year Treasury bond rose to 4.96 percent, up from 4.91 percent on Monday, following strong economic data from late September. Typically, higher yields pressure equity valuations, but some industrial sectors defied the trend. DuPont rallied 8.6 percent, and Celanese climbed 5 percent, both buoyed by strong summer profits.
Energy markets remained relatively stable, with Brent crude oil rising 0.2 percent to $103.84 per barrel and U.S. benchmark crude gaining 0.2 percent to $96.28 per barrel. These figures suggest that while central bank policies remain a volatile variable, global demand for energy remains steady.
The Missing Link in Kioxia's Failed Guidance
Despite the broad market data, several critical gaps remain in the current narrative. The report mentions that Japanese memory chipmaker Kioxia Holdings tumbled 5.4 percent initially because its guidance for the October to December period failed to meet expectations, citing "ongoing challenges in the semiconductor supply chain." However, the report does not specify what these challenges are—whether they are geopolitical, raw material shortages, or demand-side failures.
Additionally, while the Democratic Party's congressional victory is clear, the source provides no detail on the specific legislative priorities the party intends to pursue. Investors are betting on gridlock, but without a clear Democratic manifesto for the 2027 session, the market is operating on an assumption of inertia rather than a known policy roadmap.
Comments 0