
The Independent Community Bankers of America has filed a lawsuit against the Office of the Comptroller of the Currency and Comptroller Jonathan Gould. The legal action challenges the federal agency's authority to grant national trust charters to digital-asset companies .
The March 2nd rule and the 2016 interpretive letter
At the heart of the legal dispute is a final rule implmented on March 2nd and a supporting interpretive letter dating back to 2016. According to the report, the Independent Community Bankers of America (ICBA) argues that these regulatory tools are unlawful because they allow the Office of the Comptroller of the Currency (OCC) to charter crypto companies that do not operate as fiduciaries.
The ICBA contends that by utilizing these specific guidelines, the OCC is essentially creating a two-tiered banking system. While traditional community banks must adhere to strict federal oversight, the ICBA claims that digital-asset firms are being gratned the prestige of a federal charter without the corresponding legal obligations that have defined American banking for decades.
Coinbase and the Trump-linked trust company
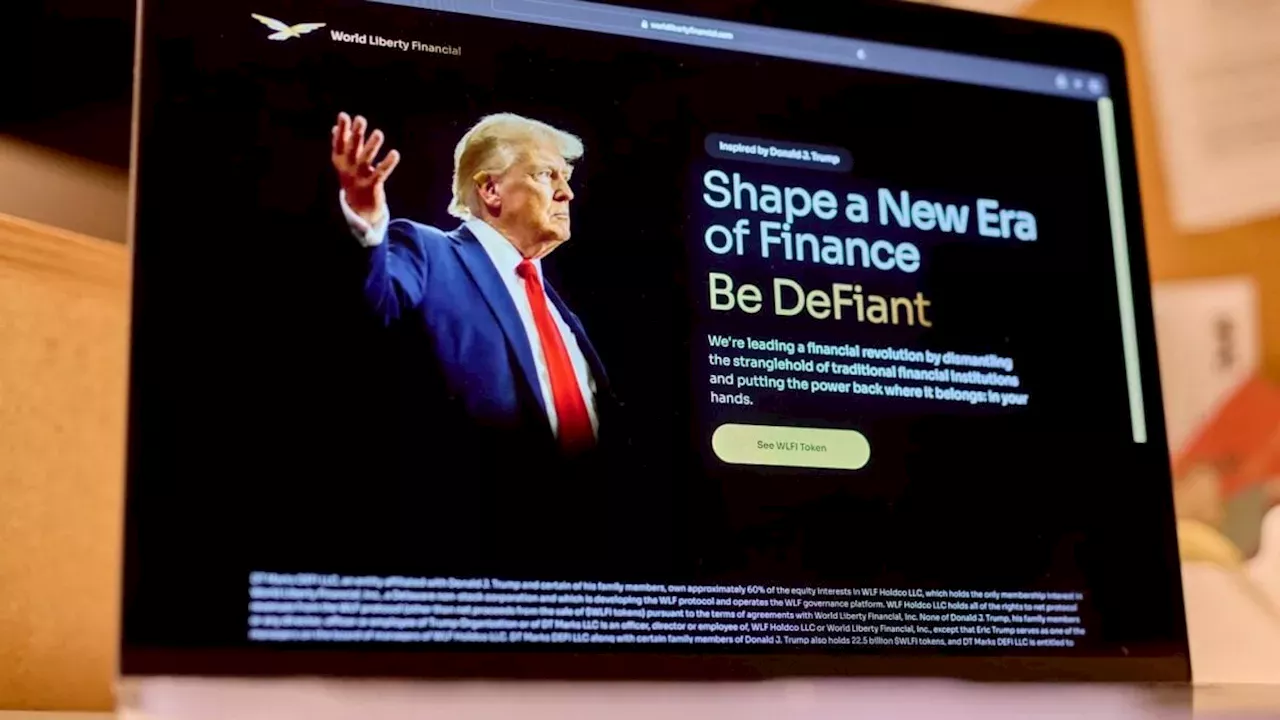
The lawsuit highlights specific instances where the Office of the Comptroller of the Currency has already extended these privileges. as the report says, the ICBA pointed to a conditional charter granted to Coinbase as well as a trust company associated with the family of former President Donald Trump.
The Independent Community Bankers of America argues that these charters provide a dangerous level of "credibility." By appearing as federally chartered entities, these crypto firms can attract customers under the guise of national bank stability, even though they are not held to the same capital standards as traditional lenders.
Protego Holdings and the bypass of FDIC insurance
A primary target of the litigation is Protego Holdings, a firm that received a conditional charter in February after a previous approval from 2021 expired in 2023. Protego Holdings intends to offer token-issuance, crypto lending, trading, and custody platforms, though it plans to keep its fiduciary activities limited to ancillary services.
The ICBA warns that allowing Protego Holdings to operate under a national trust charter would enable the firm to preempt state-level consumer protection laws. Furthermore, the ICBA argues that such a charter allows Protego Holdings to avoid the essential requirements of FDIC insurance and community-lending duties, which are mandatory for traditional national banks.
The struggle between community lending duties and digital-asset competition
This legal battle reflects a broader systemic tension between the legacy financial sector and the emerging Web3 economy. For over a century, the "national bank" designation has been a pact: in exchange for federal backing and nationwide operation, banks must support local communities through lending and maintain rigorous capital reserves.
The Office of the Comptroller of the Currency views this differently, describing its chartering push as a policy designed to foster greater market competition. By allowing entities to become national banks while engaging in "legally permissible activities," the OCC believes it is modernizing the financial system to accommodate digital assets.
Whether a Washington judge will vacate the Protego charter
The resolution of this case now rests with a federal judge in Washington, who must decide if the OCC exceeded its statutory authority. A critical point of contention is whether the judge will grant the ICBA's request to specifically vacate the February charter given to Protego Holdings.
Beyond the Protego case, it remains unclear if the court will issue a blanket ban preventing the Office of the Comptroller of the Currency from using the 2016 interpretive letter for future approvals. The source reports only the ICBA's allegations and the OCC's general policy stance, leaving the specific legal defense the OCC will mount in court currently unknown.
Comments 0