
The Canadian market is preparing for a major transition as federal authorities shift from political rhetoric to tangible trade and export expansion. This movement toward domestic industrial support is creating distinct pockets of opportunity acrross the TSX.
The $11.50 target for Algoma Steel in Sault Ste. Marie
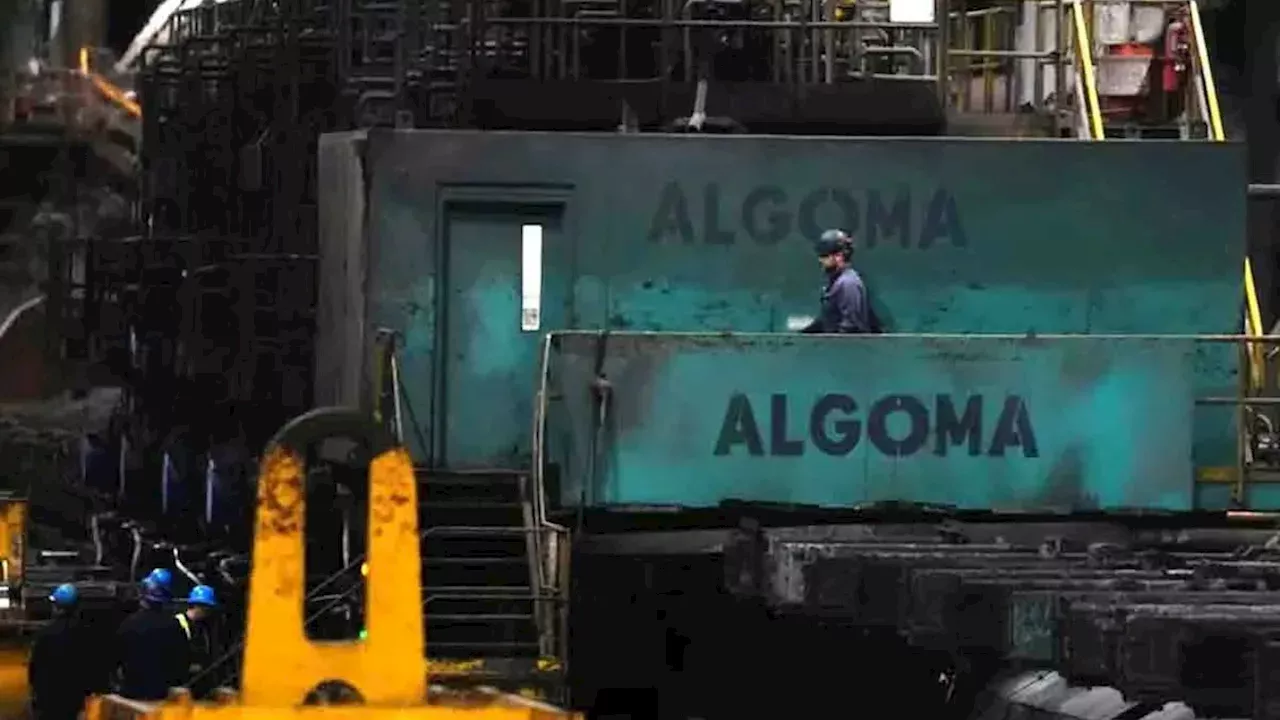
A major shift in Canadian industrial policy is creating significant upside for domestic steel producers.. According to Stifel analyst Ian Gillies, Algoma Steel is a primary beneficiary of a new infrastructure fund intended to limit foreign steel imports. Based in Sault Ste. Marie, Northern Ontario, the company has been issued a buy rating with a target price of $11.50 per share, representing a significant increase from its recent closing price of $6.63.
The potential for growth is tied to the interest shown by policymakers in Ontario and Ottawa regarding a new beam mill. This facility would allow Algoma Steel to increase its domestic production of beam products, aligning with the broader national goal of strengthening local supply chains.
A doubling of the TSX aerospace and defence index since 2025
The aerospace and defence sector is seeing unprecedented momentum within the Canadian markets. David Rosenberg of the Canadian Securities Institute has observed that the TSX-listed aerospace and defence index has seen its value double since the beginning of 2025. The report says this surge is largely attributed to a global trend of rising defence spending, which analysts believe will provide a durable growth tailwind for domestic firms.
Beyond the broad index, specific companies are seeing target price adjustments. For instance, BMO Capital Markets recently raised its target for Spartan Delta to $18, citing strong inventory and economics, while TD Cowen increased its outlook for Mullen Group to $36 following a significant deal in Colombia.. For those seeking more stability, the Global X Equal Weight Canadian Pipelines Index ETF, which offers a 4.5 percent yield, is being recommended as a way to gain exposure to expanding export infrastructure.
The 4.15 percent historical return from mid-October tax-loss selling
Strategic timing in the mid-October window could offer significant returns for disciplined investors. as CIBC Capital Markets research analyst Sid Mokhtari notes, companies that have experienced a decline of more than 20 percent and maintained average losses of roughly 1.3 percent between mid-October and mid-December are prime candidates for repurchases. Historically, this specific tax-loss selling strategy has yielded a 4.15 percent return.
The list of potential repurchase candidates is diverse, spanning from large-cap stalwarts like Canadian National Railway to smaller-cap entities such as Cogeco, Pizza Pizza Royalty, MTY Food Group, and Boston Pizza Royalties. Investors are increasingly using this window to capitalize on price recoveries driven by corporate buyback programs.
The unanswered question of Algoma Steel's $920 million debt
While the prospect of new infrastructure is bright,the financial health of industrial leaders remains a point of scrutiny. The source notes that Algoma Steel is currently carrying $920 million in debt, a significant figure that complicates its immediate balance sheet. It remains unverified whether the proposed grants from Ontario and Ottawa for a new beam mill will be suffficient to offset this liability or if the debt will continue to weigh on the company's ability to capitalize on the new trade-focused economy.
Comments 0