
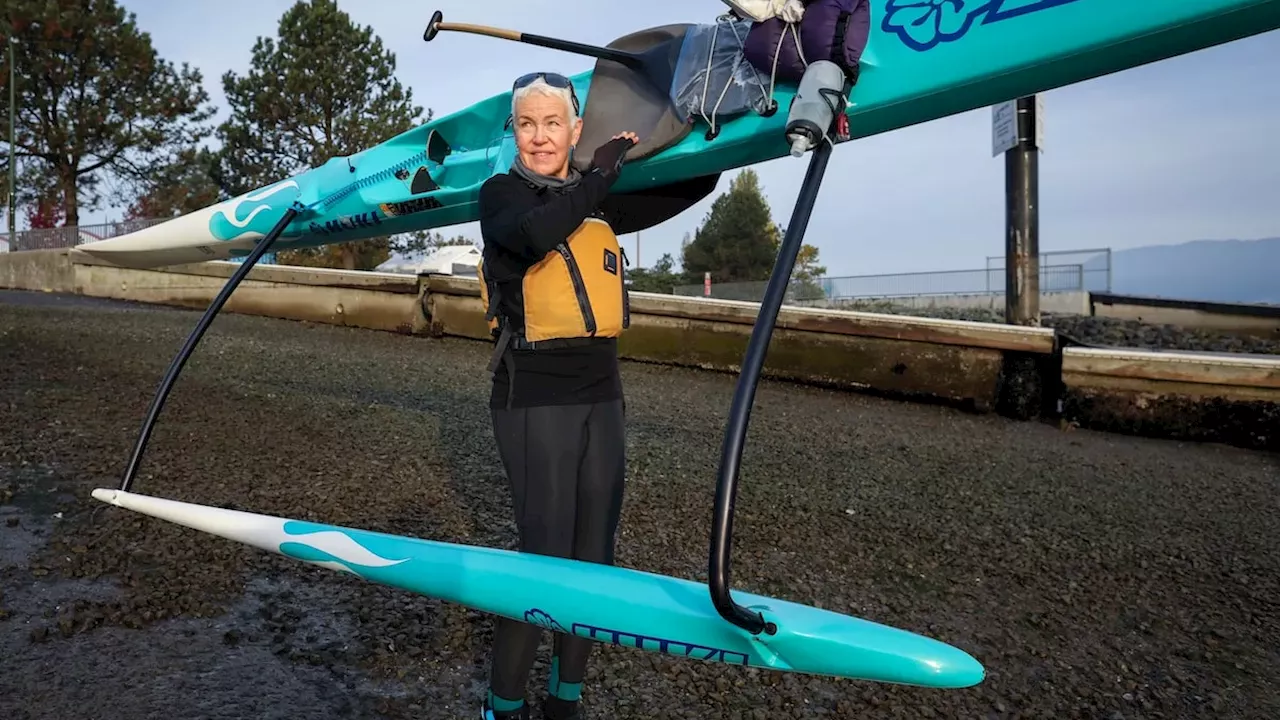
Kathleen Collin, a 67-year-old former nephrology pharmacist based in Vancouver, transitioned into retirement in 2016. after spending 33 years at BC Children's Hospital,she has traded a high-stress medical career for a lifestyle centered on creative arts and physical activity.
From BC Children's Hospital specialist to novice race car driver
For 15 years, Kathleen Collin worked within a specialized nephrology team focusing on kidney disease and transplants.. As reported in the "Tales from the Golden Age" series, the intensity of this role led to burnout, prompting Collin to retire at age 57 to reclaim her personal time. This transition, however, brought an unexpected psychological challenge: the loss of professional identity.. Collin noted that leaving a field where she was constantly consulted for critical decisions made her feel "less smart" initially.
To combat this cognitive slump, Kathleen Collin has aggressively pursued new intellectual and physical challenges. She has returned to playing the flute, taken up watercolor painting, and is currently studying French to become bilingual. Her physical activity is equally diverse, ranging from paddling an outrigger canoe to qualifying as a novice race car drievr at a track in Mission, B.C. This shift illustrates a broader trend among high-achieving professionals who must "retire to something" rather than simply "retire from something" to avoid the depression often associated with the loss of a high-status career.
The RRSP trade-off and the mortgage regret
Financially, Kathleen Collin benefited from a defined-benefit (DB) pension plan, a rarity in the modern gig economy that provided the stability necessary for an early exit from the workforce. According to the source report, Collin also maximized her Registered Retirement Savings Plans (RRSPs) throughout her career, following a philosophy of financial responsibility instilled by her mother. However, this disciplined approach has led to a retrospective regret regarding the allocation of those funds.
Collin now believes she may have over-prioritized her RRSPs at the expense of other lifestyle assets. She expressed a wish that she and her husband—who also holds a DB pension—had used those funds to pay off their mortgage sooner or invest in a larger residence. This highlights a common tension in retirement planning: the balance between liquid long-term savings and the immediate utility of debt-free homeownership or improved living conditions during one's most active years.
The age 94 financial horizon
Despite her regrets over specific allocations, Kathleen Collin's overall financial trajectory remains positive. A financial planner consulted by Collin a year prior to her retirement estimated that her assets would sustain her until approximately age 94. This specific projection is a critical benchmark for Collin, as she notes that the women on her father's side of the family frequently lived well into their 90s, creating a legitimate concern about outliving her capital.
While the fear of longevity risk persists, Collin maintains a pragmatic outlook, stating she would be content even if she died with only one dollar in the bank, particularly as she has no children to inherit her estate. this perspective shifts the focus of her later years from wealth accumulation to wealth utilization , though the exact details of her current annual spending and the specific terms of her DB pension remain undisclosed.
Canadian business support amidst U.S. trade tensions
Beyond her personal finances, Kathleen Collin has linked her spending habits to geopolitical concerns. She mentioned that current trade tensions with the United States have motivated her and her husband to prioritize spending with Canadian businesses to support the domestic economy over the long term. This suggests that for some retirees, consumption is not merely about personal pleasure but is viewed as a form of civic contribution.
However, several points remain unverified in the account. The source does not specify which particular trade policies or "trade war" events are driving Collin's shift in spending, nor does it provide the name of the financial planner who set her age-94 horizon. Furthermore, while Collin advocates for early retirement, the report only presents the perspective of someone with a defined-benefit pension, leaving open the question of how this "live for yourself" model would apply to retirees relying solely on volatile market-based investments.
Comments 0