
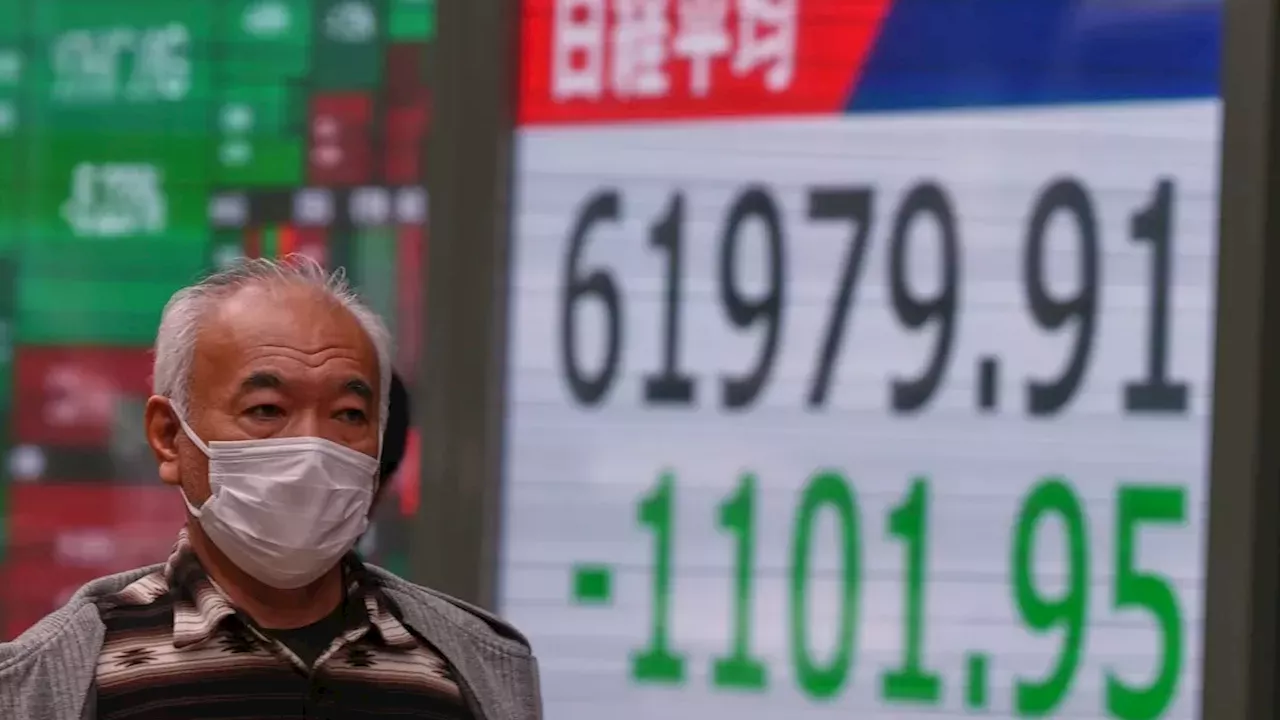
On November 4, 2026, major Asian stock indices experienced significant downturns as investors reacted to shifting AI valuations and the aftermath of U.S. midterm elections. Japan's Nikkei 225 and South Korea's Kospi led the regional decline, reflecting a broader retreat from high-growth technology sectors.
The 10.8% Kioxia tumble and the Nikkei's May-low retreat
The Nikkei 225 index in Japan fell 3 .6% to close at 60,835.36 points on Wednesday, marking its lowest level since early May. This decline was driven by significant outflows from technology-heavy holdings, including an 8% slump in SoftBank Group, a major investor in OpenAI. The volatility was further exacerbated by Kioxia Holdings, which saw its shares tumble 10.8% after issuing guidance for the October to December period that missed market expectations.
South Korean marets also faced intense selling pressure, with the Kospi index dropping 3.2% to 5,466.83 points. According to the report, key exporters such as SK Hynix and Samsung Electronics saw declines of 3.2% and 1.8%, respectively... In contrast, markets in China and Hong Kong showed more resilience; the Shanghai Composite edged 0.1% lower to 3,603.83 points, while the Hang Seng declined by a marginal 0.2%.
From financing costs to the power grid: Stephen Innes's warning
The narrative surrounding artificial intelligence is shifting from pure capital expenditure to the physical realities of infrastructure. Stephen Innes of SPI Asset Management noted that investors are transitioning from worrying about financing costs to concerns regarding how politicians might control the power grids essential for energy-intensive AI data centers. this shift suggests that the "AI trade" is entering a more complex phase involving utilitty and regulatory stability.
Rising component costs are also beginning to impact the margins of major technology leaders. Apple Inc. saw its stock fall 1.9% despite reporting stronger-than-expected quarterly revenue and profit. The company indicated that escalating costs for memory chips—driven by the surge in demand for AI data centers—will likely result in lower profit margins per dollar of revenue during the final quarter of the year.
The midterm election's regulatory shadow and the S&P 500's history
The political landscape following the November 3 U.S. midterm elections has introduced a layer of regulatory uncertainty to global markets. While Brock Weimer,an analyst at Edward Jones, pointed out that the S&P 500 has delivered a positive return in every six-month period following a midterm election since 1970, the immediate market reaction remains sensitive to potential policy shifts. Investors are currently weighing the risks of a Democratic sweep of Congress, which could lead to stricter regulations on AI development.
Wall Street's preference for a divided government acts as a hedge against sweeping economic changes. Even with the potential for stricter oversight, any significant regulatory measures would still be subject to the veto power of a president like Donald Trump, adding a layer of political calculus to current trading patterns.
Will the 4.96% Treasury yield dampen AI growth?
A critical unanswered question for the market is whether rising bond yields will eventually stall the massive investment cycles currently fueling the tech sector. As the 10-year Treasury yield climbed to 4.96% from 4.91%, the increasing cost of capital poses a direct threat to the valuations of high-growth stocks. it remains unverified whether the current momentum in AI spending can withstand a sustained period of higher interest rates.
While the broader tech sector struggled, the market showed signs of extreme selectivity. companies like DuPont and Celanese saw gains of 8.6% and 5%, respectively, driven by stronger-than-anticipated profits. Simultaneously, the commodities market saw slight dips, with Brent crude falling 0.5% to $103.14 a barrel, adding further complexity to the inflation and interest rate outlook that will ultimately dictate the next move for growth stocks.
Comments 0