
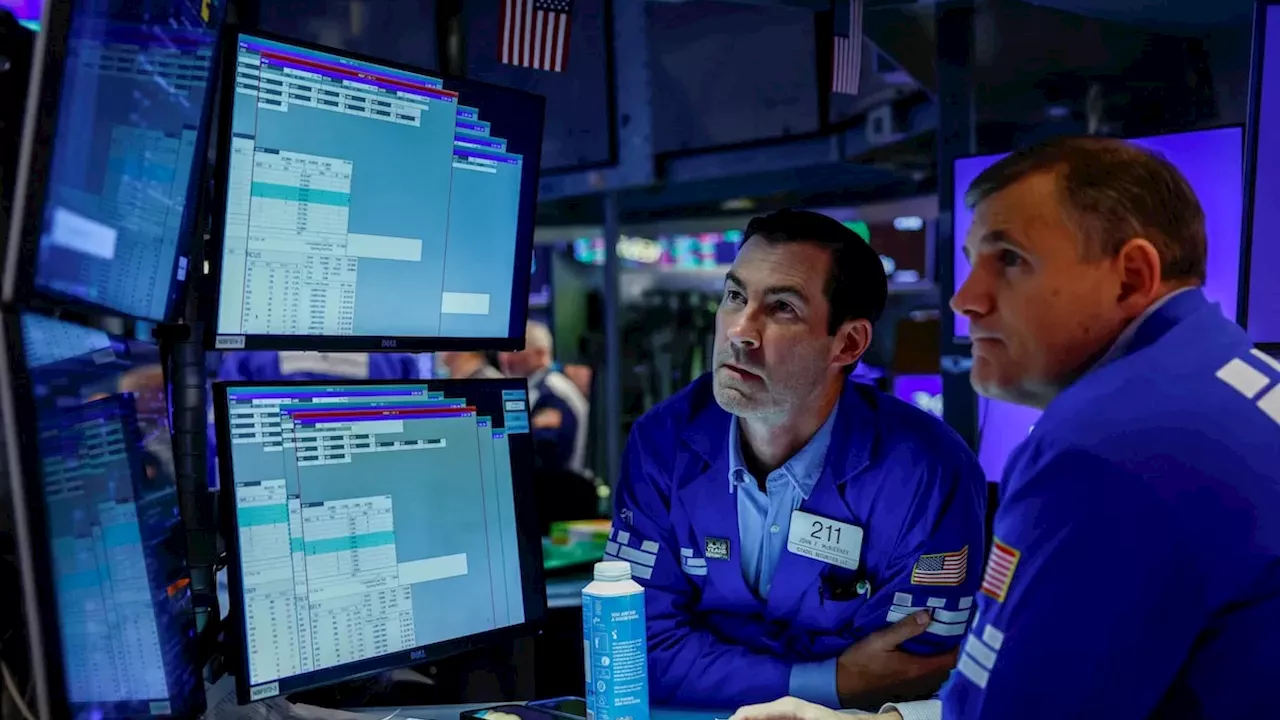
Global equity markets displayed a fragmented performance on Tuesday as investors weighed technological optimism against rising capital costs. While the S&P 500 and Nasdaq saw gains, the Dow faced downward pressure amid shifting energy policies and AI skepticism.
The massive upfront cost of AI infrastructure
The current market volatility is being driven by growing anxiety regarding the economic viability of artificial intelligence.. As reported by the source, there is a rising chorus of concern that the revenue generated by AI platforms may not be enough to cover the enormous expenses required to build and maintain specialized machine learning models.
My Bui, an economist at fund manager AMP, noted that investors are worried about the potential for massive write-downs as AI infrastructure ages and depreciates. This concern is compounded by a broader economic trend of widening corporate credit spreads and increasing government bond yields, both of which are driving up the cost of financing for major tech expansions.
A 1.27% slide in Brent crude following Trump's policy shift
Energy markets reacted sharply to President Trump's decision to waive sanctions and tariffs on Russian gas. According to the report, Brent crude fell 1.27 per cent to $108.50 a barrel as investors moved to take profits following the policy announcement.
While the administration's move aims to stabilize fuel supplies amidst Middle Eastern political turbulence,some analysts remain skeptical of its efficacy. Market analyst Priyanka Sachdeva described the decision as "another desperate attempt to keep oil prices in check ahead of the US mid-term elections." Furthermore, experts suggest this policy shift may have a limited impact on the actual physical supply disruptions occurring in the Strait of Hormuz.
European markets face declines in the CAC 40 and DAX
The uncertainty in the energy and tech sectors has spilled over into intrnational indices, with much of Europe trading in the red. The French CAC 40 saw a significant drop of 1.39 per cent, while Germany's DAX fell by 1.12 per cent. Other regional players also struggled, with the FTSE 100 slipping 0.94 per cent and the Nikkei 225 closing 0.62 per cent lower in Japan.
In contrast to the European downturn, the Hang Seng in Hong Kong provided a small buffer for global sentiment, recording a modest 0.52 per cent increase. Meanwhile, commodity markets showed mixed signals, with gold prices edging up slightly to $4,171.65 an ounce, even as West Texas Intermediate (WTI) crude hovered near $101.40 a barrel.
Will China's 4.5% GDP growth stabilize the outlook?
As the week progresses, several critical macroeconomic data poits remain unverified and could dictate the next market move. Investors are looking closely at China's upcoming third-quarter GDP data, specifically whether it can meet the expected 4.5 per cent growth rate to support long-term economic targets. There is also uncertainty regarding Canada's September Consumer Price Index and whether it will signal an acceleration in inflation.
Beyond macro data, the market is waiting to see if individual corporate earnings can provide a directional cue. Specifically, it remains to be seen how incumbents such as Cleveland-Cliffs Inc., Fifth Third Bancorp, Steel Dynamics Inc., and W.R.. Berkley Corp will report their guidance. These results will be instrumental in determining if the market continues to embrace the AI narrative or retreats due to the rising cost of capital.
Comments 0